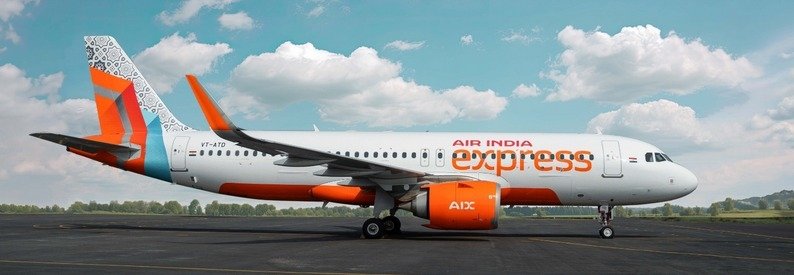
Indian Aviation Sector Faces Capacity Constraints Amid Fleet Expansion Challenges
The Indian aviation market continues to witness a paradox of rapid passenger growth coupled with significant supply-side bottlenecks. While domestic carriers are placing record-breaking aircraft orders to keep pace with the world’s fastest-growing major economy, the industry remains tethered by lingering delivery delays and engine maintenance issues that have curtailed potential capacity.
Recent data highlights that major players, including market leader IndiGo and the Tata Group-owned Air India, are aggressively expanding their order books. These airlines are banking on the projected rise in middle-class air travel demand, which is expected to see India become one of the top three global aviation markets by the end of the decade. However, the operational reality on the tarmac tells a different story, as the global supply chain crisis continues to impact aircraft manufacturers’ ability to meet delivery timelines.
Supply Chain Hurdles and Grounded Assets
The primary challenge currently facing Indian carriers is the limited availability of spare parts and engine servicing capacity. Several aircraft are currently grounded across the country’s fleet due to issues related to Pratt & Whitney engine reliability. This has forced airlines to scramble for wet-lease arrangements or extend the service life of older jets to maintain their flight schedules.
Analysts suggest that these grounded assets are inflating operational costs, as airlines are forced to shell out higher premiums for leased capacity during peak travel seasons. Furthermore, the volatility in aviation turbine fuel (ATF) prices, coupled with a fluctuating rupee, adds another layer of complexity to the financial health of low-cost carriers (LCCs) that operate on thin margins.
Infrastructure and Regional Connectivity
While the fleet expansion story dominates headlines, the government’s focus remains steadfast on the UDAN (Ude Desh ka Aam Nagrik) regional connectivity scheme. The Ministry of Civil Aviation has been pushing for the development of smaller airports to connect Tier-2 and Tier-3 cities. Yet, the rapid expansion of airport infrastructure is struggling to keep pace with the growth in passenger footfall. Major metros like Delhi, Mumbai, and Bengaluru are already operating near peak capacity, leading to congestion and delays that threaten to dampen the overall passenger experience.
The government’s push to privatize and modernize existing brownfield airports, along with the construction of massive greenfield projects like the Noida International Airport, is seen as a long-term solution. These infrastructure upgrades are critical to ensuring that the anticipated fleet growth can actually be utilized effectively without creating a gridlock in the skies.
Future Outlook and Competitive Dynamics
Despite the headwinds, the outlook for the Indian aviation sector remains bullish. With the consolidation of Air India under the Tata umbrella, the market is shifting toward a more structured duopoly, which experts believe will lead to more rationalized pricing and improved service standards.
For the passenger, the immediate future holds a mix of higher fares during peak times and an improved network as new aircraft finally arrive. As international carriers also look to increase their footprint in India, the domestic aviation sector is entering a transformative phase. The ability of Indian airlines to navigate the current engine and delivery bottlenecks will ultimately define their profitability in the fiscal years ahead. The focus is shifting from mere survival to sustainable scaling, ensuring that the Indian aviation sector remains the jewel in the crown of the nation’s transportation infrastructure.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News