The evidentiary challenges of digital communication in tax litigation
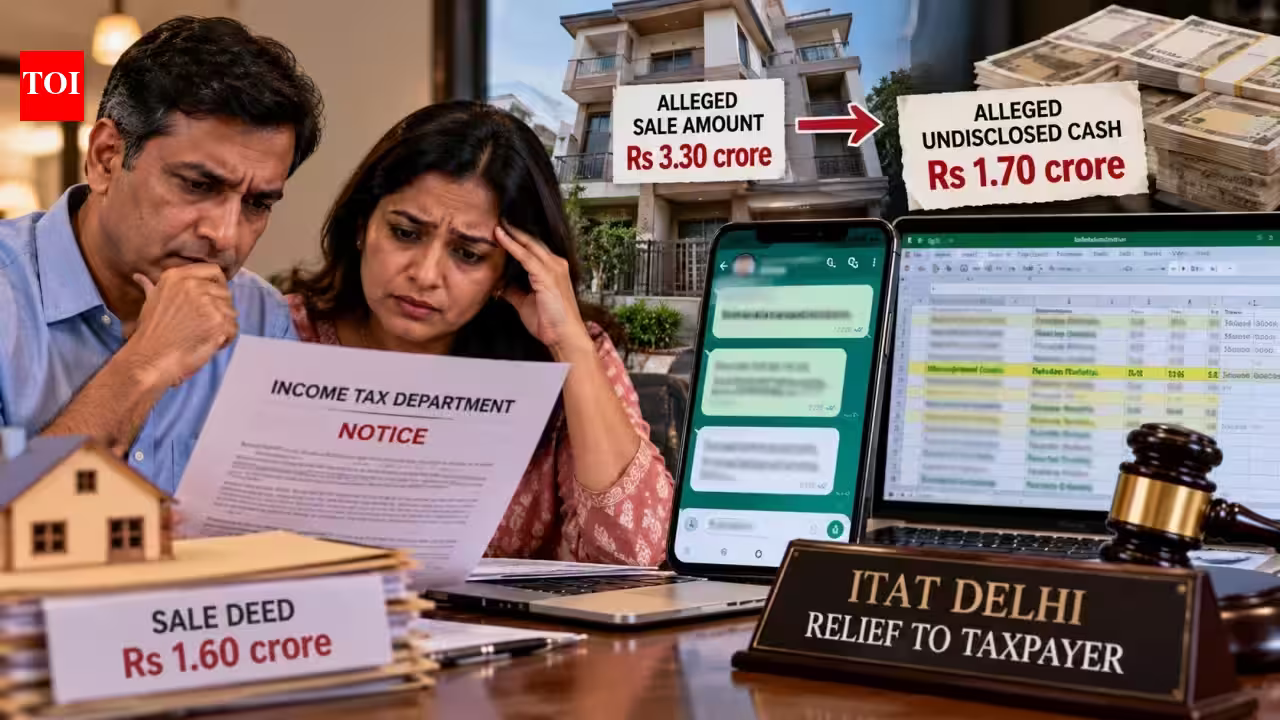
The recent ruling by the Income Tax Appellate Tribunal (ITAT), Delhi, underscores a critical juncture in Indian tax administration: the friction between modern digital evidence and established legal principles of proof. As the Income Tax Department increasingly relies on data recovered from seized devices—such as WhatsApp messages, Excel spreadsheets, and informal digital logs—the burden of proof remains a cornerstone of fair assessment. In the case involving a couple accused of undisclosed property-related cash receipts, the tribunal made it clear that while digital trails are powerful tools for investigators, they are not self-executing substitutes for substantive evidence.
The department’s case rested on the assumption that a sale consideration, documented at Rs 1.60 crore in a registered deed, was actually supplemented by Rs 1.70 crore in cash. This conclusion was drawn primarily from informal data found during a 2021 search. However, the ITAT’s intervention highlights that the mere presence of numbers in a digital chat or a spreadsheet does not constitute an “unexplained cash receipt” under Section 69A of the Income Tax Act. For such evidence to hold up, it must be corroborated by clear financial trails and adhere to the rigorous standards of administrative due process.
Procedural safeguards and the right to cross-examination
A central theme in this ruling is the importance of the right to cross-examine. In the Indian legal system, the ability to challenge the source and veracity of evidence is a fundamental requirement of natural justice. The ITAT observed that the Assessing Officer (AO) leaned heavily on statements and materials attributed to third parties without affording the taxpayers an opportunity to confront these individuals.
By relying on statements gathered behind closed doors without facilitating a cross-examination, the tax authority effectively denied the taxpayers the chance to contextualize the alleged transactions. The tribunal emphasized that if the department intends to build a case of tax evasion upon third-party records or digital conversations, it is duty-bound to examine those parties on oath. When the department fails to summon these individuals, the evidentiary value of their previous statements is significantly diminished. This ruling serves as a reminder that procedural compliance is not merely a bureaucratic hurdle but a vital protection against arbitrary assessments.
Legal flaws in the initiation of reassessment
Beyond the evidentiary gaps, the case also highlighted a technical failure regarding the application of Section 153C. This section allows the tax department to initiate assessment proceedings when incriminating material belonging to a person is found during a search of someone else. In this instance, the department utilized a consolidated satisfaction note intended to cover seven assessment years.
The tribunal found that the department failed to establish a specific, cogent link between the seized material and the income related to each individual assessment year. Legal scrutiny of tax notices often hinges on whether the authority has applied its mind to the specific year in question. By bunching multiple years together without identifying relevant, incriminating evidence for each period, the department’s approach was deemed legally insufficient. This decision reinforces the mandate that the tax department must demonstrate a clear nexus between the search findings and the specific financial years under audit, rather than utilizing a broad-brush approach to income addition.
The burden of proof in property transactions
The real estate sector in India has long been a focal point for tax scrutiny due to the historical prevalence of cash components in property deals. However, this ITAT order signals that the judiciary is increasingly wary of “suspicion-based” assessments. The court clarified that while the department’s findings were suggestive of a larger financial arrangement, they did not rise to the level of conclusive evidence.
For taxpayers, this ruling is a significant development. It validates the position that a registered conveyance deed is a document of high probative value. To challenge the figures written in a registered sale deed, the revenue authorities must provide evidence that is beyond mere inference or speculative interpretation of chat logs. The distinction between a “suspicious circumstance” and “admissible evidence” is the defining line that saved the taxpayers from a substantial tax and penalty liability in this instance.
Best practices for taxpayers under scrutiny
For individuals and business entities facing income tax notices based on digital seizures, this case provides a roadmap for defense. The primary lesson is that taxpayers must be proactive during the assessment phase rather than waiting for the appellate stage. This includes:
1. Requesting the formal disclosure of all material, including metadata and context, being used by the AO to build the case.
2. Formally demanding the right to cross-examine individuals whose statements or digital communications are being cited as proof of income.
3. Ensuring that legal challenges address both the substance of the claims (the cash payments) and the procedure (whether the notice was issued in accordance with the law).
As the Income Tax Department continues to leverage data analytics and digital forensics, the line between aggressive tax collection and legal overreach will remain contested. This ITAT ruling serves as a check on the department’s reliance on informal digital data, emphasizing that even in the age of big data, the principles of fairness, cross-examination, and specific legal compliance remain the bedrock of the Indian tax system. Taxpayers who are aware of these rights are significantly better positioned to defend their financial records against presumptive assessments.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News