The Structural Shift in Foreign Portfolio Investment Trends
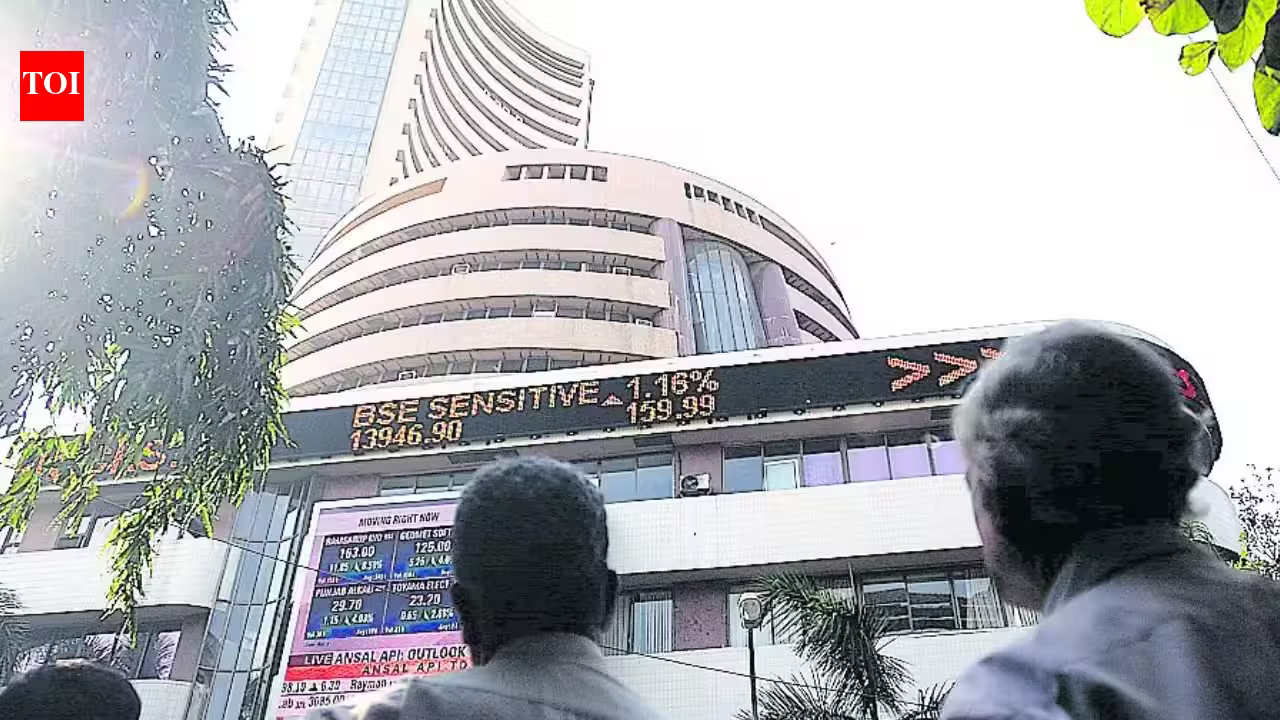
The Indian equity market is currently navigating a period of significant turbulence, characterized by a sustained retreat of foreign portfolio investors (FPIs). Recent data from the National Securities Depository Limited (NSDL) reveals a stark landscape: over Rs 44,000 crore has been withdrawn from Indian equities in October alone. When aggregated with the preceding months of the current year, total outflows have breached the Rs 3 lakh crore threshold. This figure is particularly concerning as it far surpasses the total annual outflow of Rs 1.7 lakh crore recorded in 2025.
This trend signals a departure from the historical narrative of India as a perpetual beneficiary of global capital flows. The current selling pressure is not merely a localized correction; it is a manifestation of shifting macroeconomic priorities on a global scale. As foreign capital pivots, domestic market indices, specifically the Nifty, have faced a year-to-date decline of nearly 14 percent, underscoring the influence of international institutional sentiment on local price discovery.
Macroeconomic Drivers Behind the Capital Exodus
Several interconnected macroeconomic factors are compelling global fund managers to reallocate capital away from Indian shores. Foremost among these is the resurgence of the US dollar and the persistence of elevated US Treasury yields. When the risk-free return on US government securities increases, the incentive for global investors to seek growth in emerging markets diminishes, as the risk-adjusted return profile becomes less attractive.
Furthermore, crude oil prices continue to serve as a volatile variable for the Indian economy. India remains a net importer of petroleum products, meaning that sustained upward pressure on oil prices exerts significant strain on the current account deficit and the stability of the rupee. A depreciating currency further erodes the dollar-denominated returns for foreign investors, creating a feedback loop of selling. When these factors are combined with the broader inflationary pressures that central banks are struggling to tame, the resulting environment becomes inherently hostile toward high-beta emerging market equities.
Regional Reallocation and the AI-Driven Competitiveness
An essential analytical perspective in understanding these outflows is the redirection of capital toward North Asian markets. Japan, South Korea, and Taiwan are currently experiencing a surge in foreign investment, primarily driven by their deep integration into the global artificial intelligence supply chain. The rapid expansion of AI-related infrastructure—spanning semiconductor manufacturing, high-bandwidth memory production, and data center hardware—has created a compelling growth narrative in these regions.
For global portfolio managers tasked with identifying the next phase of structural growth, the AI-led rally in North Asia offers a more direct play on technological disruption compared to India’s diversified equity basket. This represents a thematic rotation where institutional money is moving out of the defensive or consumption-heavy sectors of the Indian market to capture the accelerated earnings growth potential currently concentrated in the technology hubs of the Asia-Pacific region. This geographic preference highlights how India is increasingly competing for capital not just on local economic performance, but on its ability to offer technological differentiation that appeals to modern, mandate-driven global funds.
Domestic Earnings and Market Volatility
While global headwinds remain the primary catalyst for the current sell-off, the domestic corporate earnings cycle is under intense scrutiny. Investors are closely monitoring the performance of major IT services firms such as Wipro and HCL Technologies. These companies act as bellwethers for global demand, particularly in the banking, financial services, and insurance sectors in the United States and Europe. If these corporations signal a softening in discretionary spending or a delay in project pipelines, it reinforces the narrative that the global economy is cooling, thereby encouraging further divestment.
The volatility observed in the Indian market this year is exacerbated by the reliance on FPI flows to sustain valuation multiples. When foreign institutional selling exceeds the capacity of domestic institutional investors—such as mutual funds and insurance companies—to absorb the supply, the result is an inevitable downward pressure on price levels. While domestic inflows have remained robust, they are currently struggling to compensate for the sheer volume of foreign liquidation, leading to the broader market underperformance seen throughout 2026.
The Outlook for Indian Equities Amid Global Uncertainty
The road ahead requires a pragmatic assessment of both internal resilience and external dependencies. The Indian market is currently in a phase of valuation recalibration. As FPIs continue to reduce their exposure, market valuations are drifting toward more sustainable, long-term averages. While this process is painful for short-term sentiment, it may ultimately provide a more stable foundation for future growth.
For the remainder of the year, investors must maintain a watch on the interplay between US bond yields and domestic monetary policy. If the Reserve Bank of India manages to maintain stable interest rates while global inflation figures show signs of moderation, there is a possibility that the intensity of the selling could taper. However, as long as the cost of capital in developed markets remains high and the North Asian AI trade continues to offer perceived superior growth metrics, India will remain in a contest for global liquidity.
In conclusion, the exodus of over Rs 3 lakh crore in capital is a sobering reminder of the interconnectedness of modern financial markets. Indian equity performance is no longer dictated solely by domestic industrial output or demographic dividends; it is equally contingent on the liquidity cycles dictated by the US Federal Reserve and the strategic investment mandates of international asset managers. Investors and policymakers alike must acknowledge that maintaining a favorable investment climate now requires a more nuanced approach, focusing on fiscal discipline and demonstrating competitive growth sectors that can stand out against the backdrop of global, tech-centric investment themes.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News