The Evolution of India’s Digital Gold Market
The digital gold landscape in India has witnessed a meteoric rise, transforming how the common citizen interacts with the nation’s most trusted asset class. With assets under management estimated at approximately $3 billion, the industry has bridged the gap between traditional investment preferences and modern financial technology. By allowing individuals to invest as little as one hundred rupees, these platforms have democratized access to bullion, bypassing the logistical hurdles and security concerns associated with holding physical gold.
However, the rapid scaling of this segment has outpaced existing legislative frameworks. Until recently, digital gold existed in a regulatory vacuum, distinct from gold exchange-traded funds (ETFs) or sovereign gold bonds (SGBs). Because these products were neither classified as securities nor as commodity derivatives under the oversight of the Securities and Exchange Board of India (Sebi), investors were left vulnerable to operational risks and counterparty defaults. As the government now moves to bring this $3 billion industry under the joint supervision of the Reserve Bank of India (RBI) and Sebi, the sector stands at a critical juncture of formalization.
Navigating the Regulatory Void
The primary concern voiced by regulators stems from the nature of the custodial arrangement inherent in digital gold products. Currently, investors essentially purchase an undivided interest in gold held by a third-party vaulting service. In the absence of strict regulatory mandates, there has been no standardized mechanism to verify that the digital balance shown on a user’s mobile app is indeed matched by an equivalent weight of physical gold in a secure, audited vault.
Sebi’s warnings, particularly those issued in 2025, served as a stark reminder that digital gold platforms were not subject to the same disclosure norms, investor grievance redressal systems, or audit requirements as mutual funds or stock exchanges. The lack of regulatory arbitrage meant that while the platforms facilitated convenience, they offered little recourse in the event of a platform failure or a liquidity crunch. By transitioning these products into a framework where they are classified as securities under the Securities Contracts (Regulation) Act, 1956, the government aims to mandate transparency. This would essentially formalize the industry, ensuring that every digital unit is not just a ledger entry, but a claim on actual, vaulted physical bullion.
The Push for Mandatory Physical Backing
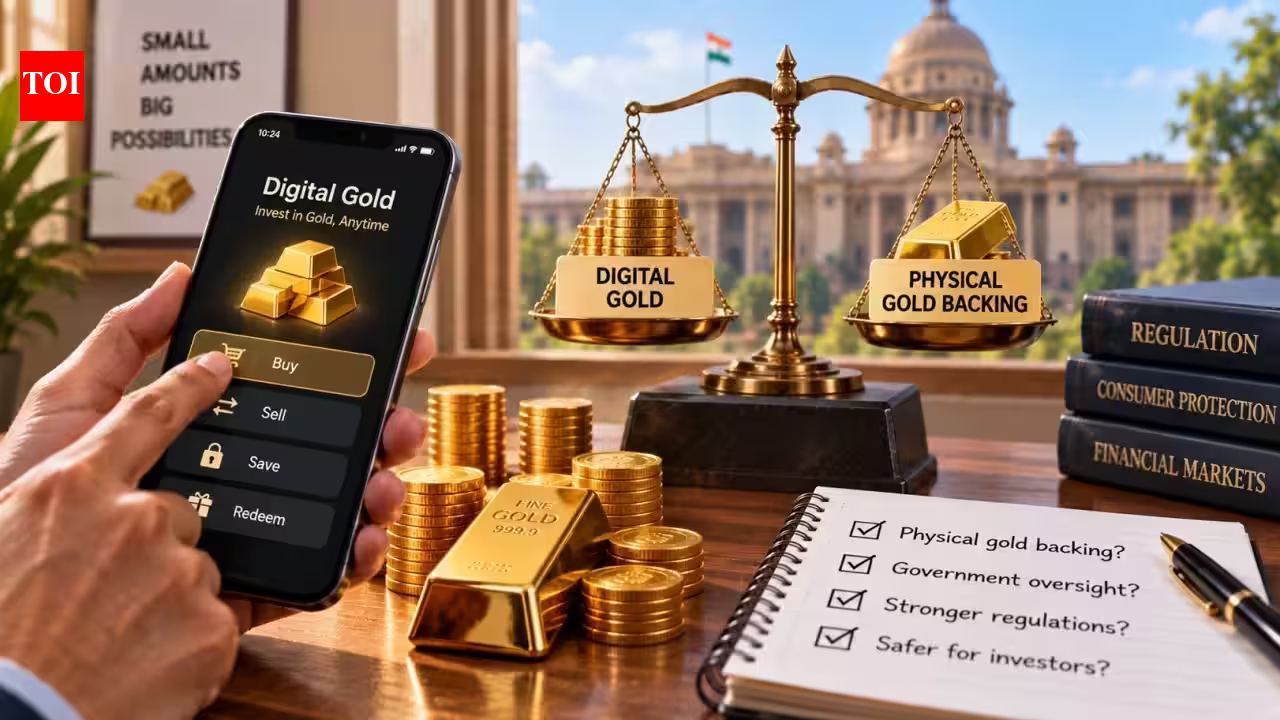
A cornerstone of the proposed regulatory overhaul is the requirement for 100 percent physical backing. Currently, the industry relies on varying degrees of internal audits and voluntary disclosures. Under the proposed regime, digital gold providers would likely be required to hold the underlying physical metal in third-party vaults that are subject to periodic, independent inspections.
This shift mirrors the operational standards seen in gold ETFs, where the underlying assets are clearly demarcated and legally protected from the insolvency of the asset manager. For the Indian consumer, this change would provide much-needed confidence. It would effectively mitigate the risk of “fractional reserve” issues—where a platform might issue digital gold credits without actually procuring the corresponding physical metal. By tightening these requirements, the government is signaling that convenience cannot come at the cost of asset integrity.
Collaboration Between RBI and Sebi
The choice of a joint oversight structure involving both the RBI and Sebi reflects the hybrid nature of digital gold. The RBI, as the guardian of the nation’s monetary stability and systemic financial integrity, is concerned with the impact of these platforms on currency circulation, potential money laundering, and the storage of precious metals. Simultaneously, Sebi’s involvement ensures that the product is treated as an investment vehicle, subject to strict reporting and market conduct standards.
This dual oversight is designed to eliminate the gaps that have previously allowed unregulated entities to operate. With banks and other major stakeholders already submitting their recommendations to the ministry, the consensus is shifting toward a unified policy that treats digital gold with the same rigor as electronic gold receipts (EGRs). This will likely necessitate a fundamental change in the operational business models of current players, requiring them to integrate with recognized vaulting agencies and adhere to strictKYC (Know Your Customer) and AML (Anti-Money Laundering) protocols.
Industry Response and Self-Regulation
In anticipation of tighter government control, the industry has proactively sought to organize itself. The formation of the Digital Precious Metals Assurance Council of India marks a significant step toward self-regulation. By bringing together major bullion providers and prominent digital platforms, the council is attempting to set industry-wide standards for purchasing, storage, and redemption processes.
For established players like MMTC-PAMP and various fintech platforms, this institutionalization is a positive development. It helps weed out “fly-by-night” operators that have historically tarnished the reputation of the digital gold sector. When the regulatory framework eventually formalizes, companies that have already invested in robust infrastructure and transparent vaulting processes will hold a competitive advantage. The focus is shifting from simply acquiring a large user base to demonstrating long-term reliability and institutional credibility.
The Future of Gold Investment in India
The formalization of digital gold will likely lead to a more mature market. While the initial years were characterized by a “land grab” approach by fintech firms, the future will be defined by compliance and safety. Investors can expect improved features, such as clearer statements of holdings, insurance coverage for vaulted assets, and more robust mechanisms for converting digital balances into physical jewellery or coins.
This transformation is crucial for the broader Indian economy. Gold remains the most significant component of household savings in India. By bringing digital gold under the regulatory umbrella, the government is not just protecting retail investors but also ensuring that the massive inflows of capital into the gold market are documented, monitored, and secure. As the sector moves from the fringes of the shadow economy into the mainstream financial ecosystem, it will likely see increased trust from a wider demographic, potentially encouraging more systematic gold savings habits that can be effectively integrated into the formal banking system. The era of unregulated digital gold is drawing to a close, replaced by a more stable, audited, and secure framework that prioritizes investor protection above all else.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News