The Anatomy of Recent Market Volatility in India
The Indian equity markets, represented by the benchmark indices BSE Sensex and Nifty50, have recently faced a significant downturn, reflecting a broader pattern of global financial turbulence. When the market erases nearly Rs 4 lakh crore in capitalization within a single morning, it serves as a stark reminder of the fragile balance between investor confidence and macroeconomic stability. This recent correction is not an isolated event but rather the cumulative result of various geopolitical frictions, inflationary pressures, and monetary policy adjustments that are currently reshaping the investment landscape.
For the Indian investor, the primary concern lies in the confluence of external shocks and domestic structural pressures. As benchmarks dip below key psychological support levels like the 22,600 mark for the Nifty50, the market narrative has shifted from growth-oriented optimism to defensive risk management. Understanding this correction requires a close analysis of the interplay between international commodities, central bank policies, and the changing behavior of institutional capital.
Geopolitical Strains and the Energy Price Conundrum
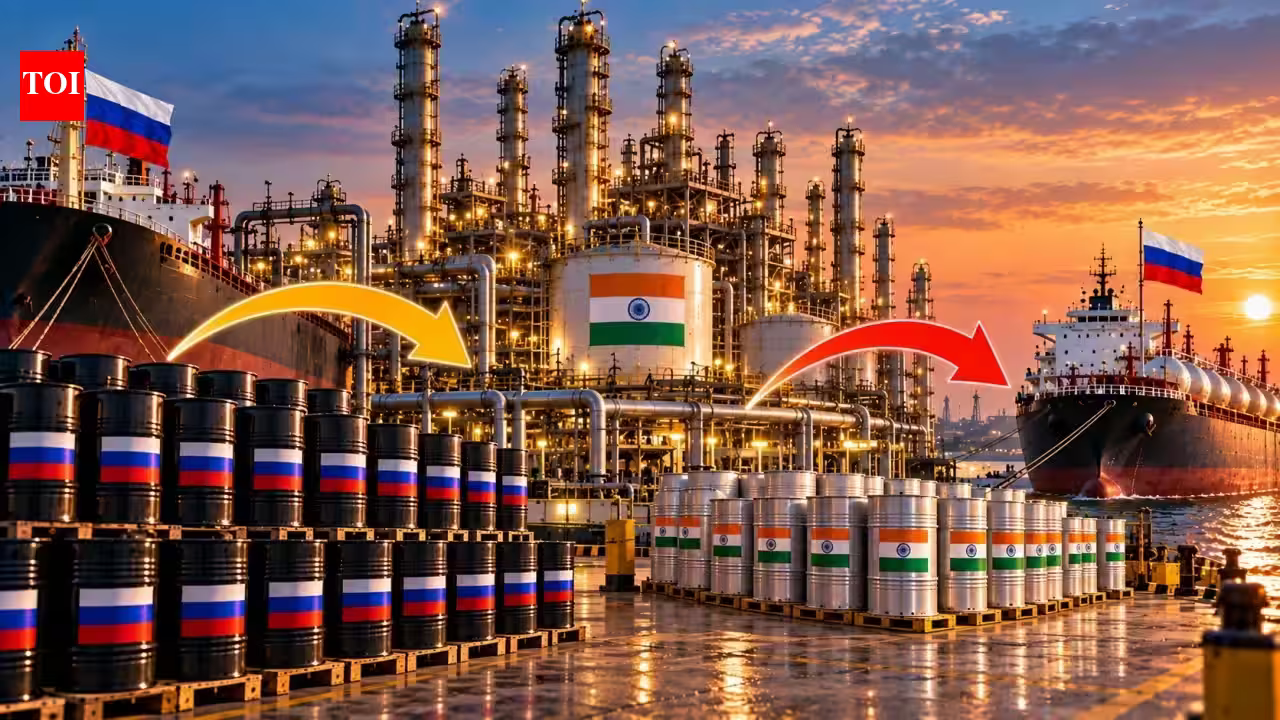
Central to the current market downturn is the volatile situation in the Middle East, which continues to cast a long shadow over global economic stability. The uncertainty surrounding potential peace deals and the ongoing regional conflicts have caused significant spikes in crude oil prices. For an import-dependent economy like India, higher oil prices are a significant headwind. When Brent crude futures climb above $107 per barrel, it directly impacts the fiscal deficit, increases import bills, and exerts inflationary pressure on the domestic economy.
The correlation between oil prices and the Indian rupee is well-documented. As oil prices surge, the demand for US dollars increases to settle import payments, leading to a depreciation of the rupee. The recent slide of the rupee toward the 96-per-dollar mark creates a dual challenge: it makes imports more expensive, thereby fueling domestic inflation, and it reduces the appeal of Indian assets for international investors who are sensitive to currency fluctuations. The market is currently pricing in this reality, as investors anticipate that higher energy costs will likely compress corporate margins across various sectors, particularly in manufacturing and logistics.
The Role of Rising Bond Yields and FII Outflows
A significant factor contributing to the current bear grip on Dalal Street is the persistent rise in global and domestic bond yields. As bond yields touch multi-year highs, they offer a safer, more predictable return compared to the inherent volatility of the equity markets. This shift in the risk-reward ratio often triggers a rotation of capital out of equities and into fixed-income securities. When capital becomes costlier and debt markets offer more attractive yields, the premium commanded by equities diminishes, causing valuations to contract.
This phenomenon is exacerbated by the behavior of Foreign Institutional Investors (FIIs). Recent provisional data highlights a concerning trend of consistent net selling, with FIIs offloading significant amounts of equity throughout the month. This reversal in FII sentiment—shifting from the net inflows seen in the summer months to a period of aggressive divestment—serves as a primary catalyst for the downward pressure on major indices. When foreign capital, which has been a major driver of India’s market rally, decides to exit, it creates a liquidity vacuum that domestic institutional investors alone struggle to fill, leading to the sharp declines observed in large-cap stocks like Bajaj Finance and across mid-cap indices.
Anticipating the Monetary Policy Response
The market is currently operating in a state of high anticipation regarding the upcoming Reserve Bank of India (RBI) Monetary Policy Committee meeting. The prevailing expectation is that the central bank will likely opt for a rate hike, following the footsteps of global peers like the US Federal Reserve, which recently increased interest rates. While a rate hike is intended to curb inflation and stabilize the currency, it also signals a period of tighter liquidity and higher borrowing costs for businesses.
For the corporate sector, this implies higher interest expenses, which could dampen capital expenditure plans and slow down earnings growth. Investors are currently adjusting their portfolios to reflect this high-interest-rate environment. By front-running these policy decisions, the market is effectively re-rating stocks based on their ability to withstand margin pressure in a higher-rate regime. The nervousness surrounding the meeting date underscores the reality that the era of “easy money” has ended, and the market must now find a new equilibrium based on fundamental value and operational efficiency.
Navigating Market Volatility and Expiry Pressures
Adding to the fundamental macroeconomic headwinds is the technical pressure associated with the monthly expiry of Nifty F&O (Futures and Options) contracts. Monthly expiry weeks are historically characterized by heightened volatility as traders and institutions square off their positions, roll over contracts, or hedge existing portfolios. In a market already sensitive to negative news, this expiry-related activity often magnifies the downward movement, as forced liquidation and hedging strategies amplify the selling trend.
Investors are advised to look beyond these temporary technical fluctuations and assess the long-term fundamentals of the sectors they are invested in. While short-term technicals and FII outflows can create intense selling pressure, the core strength of the Indian economy—driven by domestic consumption and a growing middle class—remains a vital component of the long-term investment case. However, in the immediate term, the market remains in a consolidation phase where patience and a focus on high-quality balance sheets are essential.
The current environment, while challenging, is a natural part of the economic cycle. The correction serves to flush out excesses and reset valuation benchmarks. For stakeholders, the focus must remain on identifying companies that possess strong pricing power to navigate inflationary pressures and those that maintain low debt levels, as these will be the most resilient entities once the current volatility subsides. As the market continues to grapple with the combination of global geopolitical tensions and domestic policy tightening, the path forward will likely remain uneven until clarity emerges on crude oil stabilization and the trajectory of interest rates.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News