The Evolution of India’s Financial Data Architecture
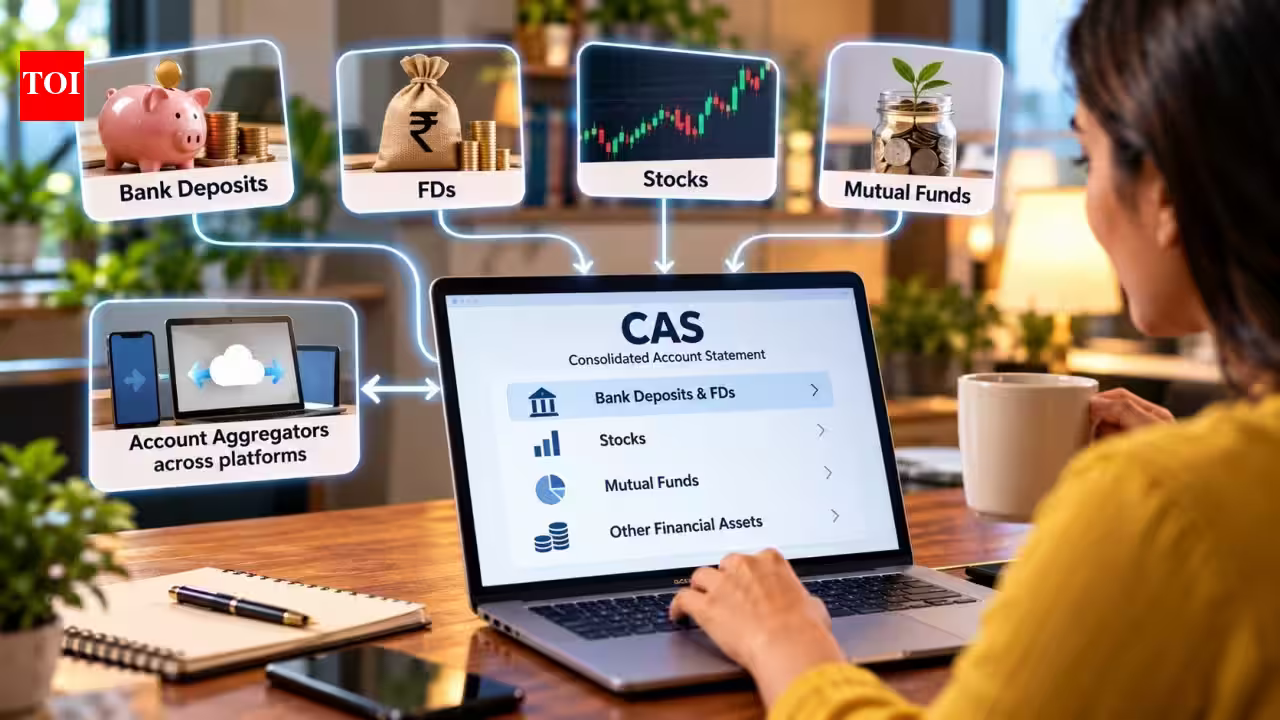
The Reserve Bank of India (RBI) has recently introduced a significant structural reform aimed at enhancing the efficiency of the nation’s digital financial ecosystem. By mandating interoperability between Account Aggregators (AAs) and allowing the integration of bank deposit data into the Consolidated Account Statement (CAS), the central bank is effectively dismantling the data silos that have historically fragmented a consumer’s financial profile. This initiative represents a strategic shift toward a more cohesive “open finance” environment, where data mobility is prioritized for the benefit of the end-user.
Since the launch of the Account Aggregator framework in 2016, the system has acted as a secure, consent-based bridge between Financial Information Providers (FIPs)—such as banks, insurers, and pension funds—and Financial Information Users (FIUs). Until now, however, the ecosystem faced limitations regarding platform compatibility. The latest directive ensures that customers are no longer tethered to a specific AA platform to access their data. By enabling seamless interoperability, the RBI is encouraging a competitive market where service providers must compete on the basis of user experience and analytical tools rather than forced platform loyalty.
Understanding the Mechanics of Interoperability
The concept of interoperability in this context is straightforward but transformative. Previously, if a consumer registered with a specific Account Aggregator to consolidate their mutual fund portfolio, they were often confined to the features and partnerships of that particular entity. With the new RBI mandate, an individual can leverage any registered NBFC-Account Aggregator to fetch their financial data from any FIP, regardless of where they initially started their digital journey.
This technical integration removes the friction of “platform lock-in.” For the consumer, it means the ability to aggregate data from disparate sources—such as a public sector bank, a private mutual fund house, and an insurance provider—into a single, unified interface through a service provider of their preference. By breaking these barriers, the RBI is essentially creating a public utility layer for financial data, similar in scope and impact to the Unified Payments Interface (UPI) in the retail payments domain.
Expanding the Scope of the Consolidated Account Statement
Parallel to the AA interoperability, the decision to incorporate fixed deposit (FD) details into the Consolidated Account Statement is a major milestone for personal financial management. Traditionally, the CAS—generated by depositories like the National Securities Depository Limited (NSDL) and Central Depository Services Limited (CDSL)—focused predominantly on securities held in demat form, such as equities, mutual funds, and government bonds.
By integrating bank deposit accounts, the CAS is evolving into a comprehensive “net worth” tracker. For the average Indian investor, who often spreads savings across multiple banks, small finance banks, and corporate deposits, this move provides a singular view of liquid assets. When viewed alongside equity and debt holdings, this allows for better asset allocation monitoring. Furthermore, by mandating that these statements also display nomination status for fixed deposits, the regulator is proactively addressing issues related to unclaimed deposits and succession planning, ensuring that families have clearer visibility into the financial assets left behind by account holders.
Strategic Advantages for Tax and Compliance
The integration of disparate financial data sources serves a dual purpose beyond simple convenience; it enhances tax transparency and improves compliance. In the current Indian tax regime, the Annual Information Statement (AIS) and Form 26AS are critical tools for filing income tax returns. However, individuals often struggle to reconcile interest income from multiple bank accounts, particularly when dealing with deposits spread across various institutions.
By centralizing information regarding fixed deposits and other interest-bearing instruments within the CAS, taxpayers can reconcile their actual earnings against the data captured by the Income Tax Department. This reduction in information asymmetry minimizes the likelihood of under-reporting income, which is a frequent cause of scrutiny for individual taxpayers. Furthermore, the ability to monitor all deposits in one statement provides an early-warning mechanism against unauthorized transactions or potential fraud. If a user identifies an account or a deposit that does not belong to them, they can address it promptly, effectively turning the CAS into a tool for financial security.
The Broader Impact on the Financial Ecosystem
The move towards a more transparent and interoperable framework serves to deepen the penetration of formal financial services in India. As data sharing becomes more standardized and secure, lenders and wealth managers can offer more personalized products based on a complete view of a customer’s financial health. For instance, a bank offering a loan can now assess a borrower’s creditworthiness using a holistic picture that includes not just their salary credits, but their entire asset base, including investments and savings deposits.
The timeline for implementation—set for completion by December 31—suggests that the regulator is committed to a rapid transition. As the Account Aggregator ecosystem matures, we can expect to see a surge in fintech innovation. Developers are likely to build sophisticated tools that use this aggregated data to provide automated financial advice, retirement planning, and personalized risk assessment models. The role of the central bank here is to provide the infrastructure, while the private sector is encouraged to build the applications that make this data actionable for the millions of Indians entering the formal financial fold.
A New Era of Financial Inclusion and Transparency
The convergence of Account Aggregator interoperability and the expansion of the Consolidated Account Statement signals the end of fragmented financial management for the Indian consumer. By prioritizing data portability and comprehensive visibility, the RBI is fostering a culture of informed financial decision-making.
While the implementation will require rigorous coordination between depositories, RTAs, and various financial institutions, the long-term benefits are substantial. Consumers gain empowerment over their own data, financial institutions gain a more accurate view of their customers, and the economy benefits from a more efficient, technology-driven allocation of capital. As these changes take effect, the Indian financial landscape will move closer to a seamless, digital-first infrastructure, fundamentally changing how households manage, protect, and grow their wealth. The transition toward a unified financial dashboard is no longer a distant possibility; it is a regulatory priority that will soon define the standard for all financial interactions in the country.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News