The Jurisprudence of Burden of Proof in Tax Raids
The discovery of large sums of cash and foreign currency during an Income Tax Department search often triggers an immediate presumption of tax evasion. Under Section 69A of the Income Tax Act, 1961, any money, bullion, jewellery, or other valuable article found in the possession of an assessee—for which they cannot provide a satisfactory explanation—may be deemed their income and subjected to heavy taxation. The recent ruling by the Income Tax Appellate Tribunal (ITAT) in Delhi serves as a critical study in how the burden of proof operates when assets recovered from a premise do not belong to the primary occupant.
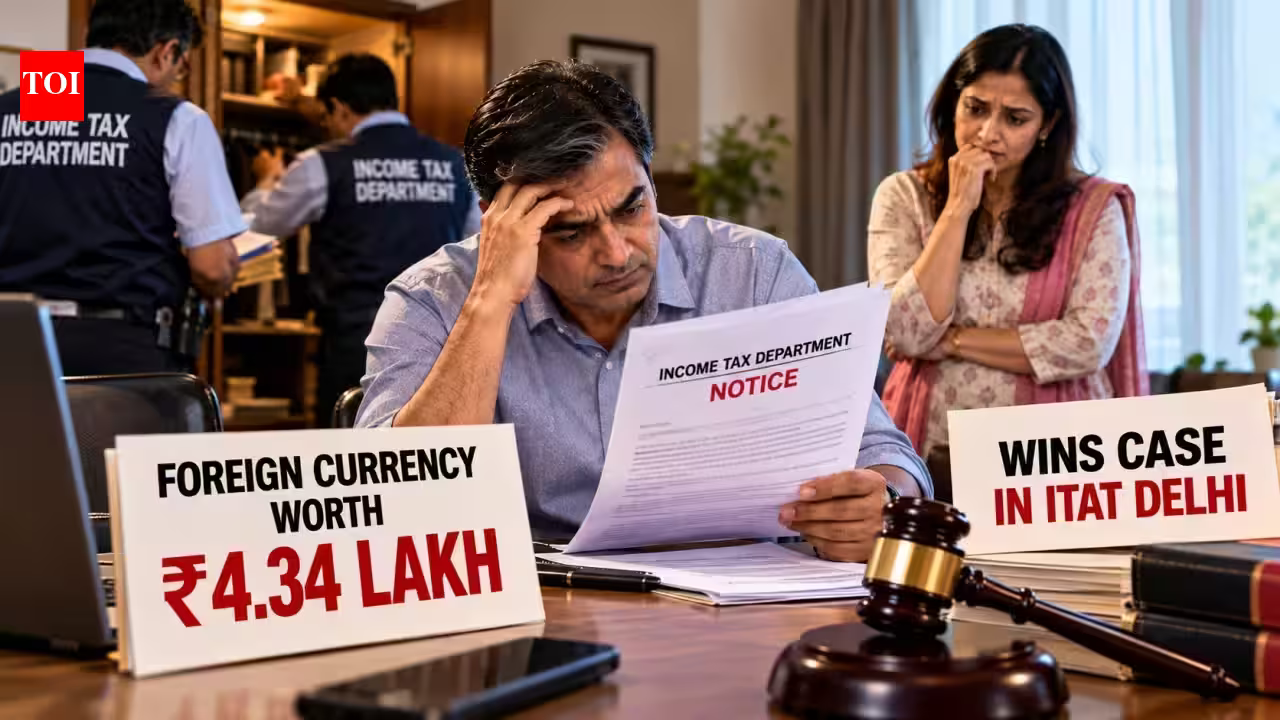
In the case of a Delhi-based company director whose residence was searched in the aftermath of the demonetisation exercise, the core legal challenge was bifurcated: one regarding a substantial domestic cash reserve of Rs 1.12 crore, and the other concerning foreign currency worth Rs 4.34 lakh. The legal battle highlights that while possession is a strong indicator of ownership in the eyes of the tax authorities, it is not an absolute determinant if the assessee can establish a credible, documented link to the actual owner.
Navigating Section 69A and the Role of Evidence
The Assessing Officer (AO) originally treated the entire haul as unexplained wealth. However, the legal trajectory of this case proves that tax litigation is as much about documentation as it is about the facts on the ground. For the Rs 1.12 crore in domestic currency, the director successfully demonstrated that the funds were recorded in the books of accounts of the corporate entity he managed. By aligning the physical cash with the ledger entries of the company, the director shifted the narrative from “unexplained income” to “corporate liquidity management.”
The foreign currency issue, however, presented a more complex challenge. Since foreign exchange is governed by strict regulations, the tax authorities are often more skeptical. The director’s defense relied on the occupational profile of his sister-in-law, an airline employee who frequently traveled internationally. The crucial element that ultimately swayed the ITAT was the written confirmation provided by the sister-in-law, which was further bolstered by the fact that the initial investigation team had refrained from confiscating the currency during the search operation. This contradiction between the investigative findings and the subsequent assessment order formed the bedrock of the taxpayer’s successful defense.
Corporate Transparency and Financial Documentation
For business professionals and corporate directors in India, this case underscores the necessity of maintaining meticulous records, especially when personal and corporate funds intersect. The Delhi director’s ability to defend the Rs 1.12 crore stemmed entirely from the company’s rigorous accounting practices. In the Indian tax environment, where cash withdrawals can trigger scrutiny from the Financial Intelligence Unit and the Income Tax Department, having a clear audit trail is the only defense against the presumption of unaccounted wealth.
The lesson here is profound: when a company manages large amounts of physical cash, every transaction must be reflected in the books before the money is moved. Relying on post-hoc justifications during an assessment is rarely effective. By ensuring that the cash withdrawal from the eleven corporate accounts was documented and accounted for, the director provided the Commissioner of Income Tax (Appeals) with the necessary justification to delete the additions to his income. Without that paper trail, the courts would have had little scope to provide relief, regardless of the verbal explanations offered.
Foreign Exchange Regulations and Personal Compliance
The aspect of the case involving the foreign currency provides a vital reminder regarding the Foreign Exchange Management Act (FEMA). Many Indian residents are unaware of the limits and regulations governing the possession of foreign currency. Under Regulation 3 of the Foreign Exchange Management (Possession and Retention of Foreign Currency) Regulations, 2015, residents are permitted to retain foreign currency notes up to the equivalent of $2,000 without restriction, provided the currency was legally acquired.
This case serves as a warning for families living in shared households. If an individual holds assets belonging to another family member, there must be a formal acknowledgment or an understanding that explains the possession. The sister-in-law’s written statement was the pivot point of the legal victory. Without her explicit admission that the funds were hers and that they were held in trust by the director for convenience, the ITAT would have been justified in upholding the tax demand. In cases involving family assets, ambiguity is often treated as tax evasion.
Analytical Perspectives on Tax Litigation Strategy
From a strategic legal perspective, the failure of the Assessing Officer to rebut the taxpayer’s arguments played a significant role in the tribunal’s final decision. The ITAT noted that the department failed to counter the evidence regarding the sister-in-law’s employment or the nature of her international travel. In Indian tax law, the Assessing Officer’s role is to act as a quasi-judicial authority; if the officer ignores evidence provided by the taxpayer without providing a logical, factual rebuttal, the CIT(A) or the ITAT is likely to intervene.
This case highlights a common flaw in aggressive tax assessments: the tendency to overlook circumstantial evidence that favors the taxpayer. For taxpayers, the takeaway is that litigation is an endurance sport. The director had to fight his case through multiple stages, including a remand by the ITAT that initially went against him. Persistence, when coupled with corroborating evidence, remains the most effective tool in challenging tax orders. Taxpayers must ensure that they do not simply accept the AO’s order, but systematically challenge each finding with supporting documentation.
Concluding Insights for Indian Taxpayers
As the Income Tax Department continues to leverage data analytics and post-demonetisation monitoring tools, the risk of “unexplained money” notices remains high. Business owners must be particularly careful when holding cash at residences, as the law views the occupant of the premises as the presumptive owner of all assets found therein.
Ultimately, this ruling reinforces the principle that possession does not equate to ownership if there is a credible, evidence-backed narrative to the contrary. However, this defense is only as strong as the evidence supporting it. Whether it is corporate accounting records or a family member’s formal written statement, the clarity of the documentation is what separates a successful legal appeal from a permanent tax liability. For the modern Indian professional, this case serves as a definitive roadmap for protecting one’s assets against the scrutiny of tax authorities through professional management and proactive record-keeping.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News