
India Faces Oilseed Crisis: Rapeseed Sowing Hits Decade Low
India’s agricultural landscape is bracing for a supply crunch as rapeseed sowing for the 2026/27 season has plummeted to its lowest level in a decade. With planting currently tracking 25% behind last year’s pace, the shortfall signals a tightening of domestic oilseed balances that will likely reverberate through the edible oil market well into 2027.
A Perfect Storm of Environmental Hurdles
The current crisis is primarily driven by an acute moisture deficit across India’s agricultural heartlands. Key mustard-producing regions in northwest and central India—specifically Rajasthan and Haryana—suffered from below-normal monsoon rains earlier this year. As farmers headed into the winter rabi season, they were met with parched soil and a critical shortage of irrigation water.
With the optimal planting window rapidly closing, analysts believe it is virtually impossible to recover the lost acreage. The logistical and climatic constraints have left the total sown area at approximately 4 million hectares as of early November, a deficit that suggests a significantly smaller harvest when the crop reaches maturity in early 2027.
Market Sentiment and Domestic Pricing
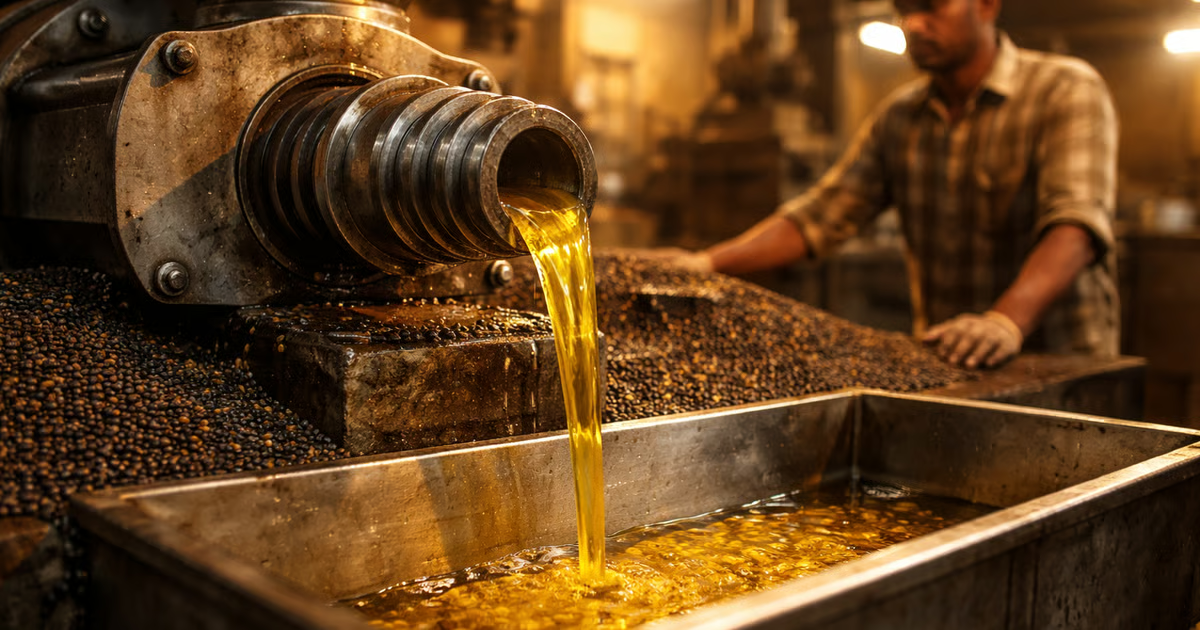
The outlook for the domestic rapeseed complex has turned decidedly bullish. Despite current mustard seed prices trading comfortably above the government’s Minimum Support Price, the supply-side reality is overshadowing market sentiment. Domestic crushers, who have already been grappling with reduced throughput since mid-2026 due to inventory shortages, are now facing the prospect of a sustained raw material drought.
The government is attempting to soften the blow to retail consumers by reducing basic customs duties on major crude edible oils. While these fiscal measures are intended to facilitate higher inflows and curb price spikes during the high-demand festival season, they also highlight the administration’s recognition that domestic production will be insufficient to meet demand.
Shift Toward Import Dependence
As domestic rapeseed oil availability shrinks, India’s reliance on foreign vegetable oils is poised to accelerate. Historically, India has been a massive importer of palm, soy, and sunflower oils; this structural dependency is now intensifying. Trade data indicates that October 2026 imports rebounded significantly, and current forecasts suggest this upward trend will continue as importers look to bridge the domestic supply gap.
For global exporters in regions ranging from South America to the Black Sea, this presents a sustained opportunity for robust sales. India is expected to remain a steady buyer of edible oils throughout the 2026/27 cycle, providing a floor for demand even if international price volatility persists.
Strategic Outlook for Stakeholders
The industry must now pivot to manage a high-cost environment. For domestic crushers, the priority is securing seed supplies and diversifying procurement strategies to manage compressed margins. Meanwhile, importers and refiners are urged to maintain a broad portfolio of origins to mitigate risks associated with logistics and geopolitical shifts in the global oil trade.
Risk management will be paramount as the market navigates this transition. As weather-related disruptions continue to threaten the rabi season, stakeholders should prepare for continued upward pressure on domestic seed prices and a market that remains heavily incentivized to prioritize imports over localized production.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News