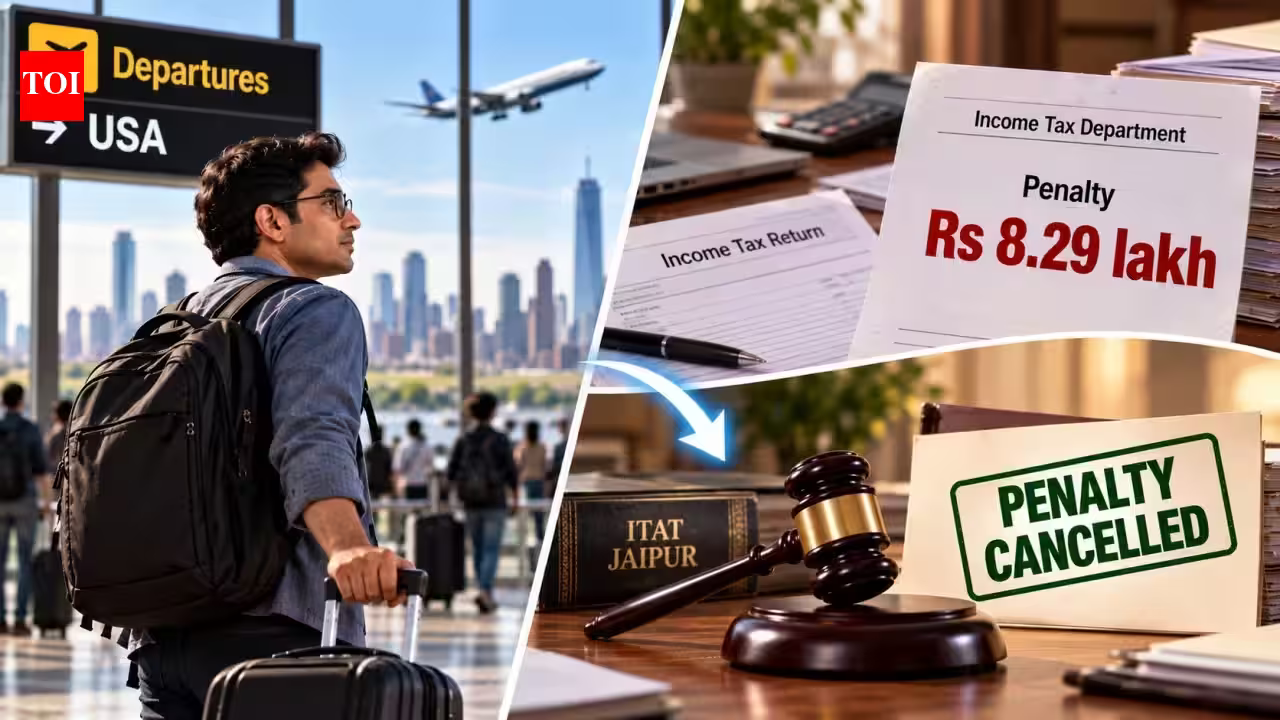
The complex landscape of Indian income tax laws often presents significant challenges for professionals relocating abroad. The recent ruling by the Income Tax Appellate Tribunal (ITAT) in Jaipur serves as a critical precedent for taxpayers who inadvertently fail to meet compliance deadlines during major life transitions. By canceling a penalty of over Rs 8 lakh, the tribunal has underscored the importance of distinguishing between intentional tax evasion and procedural lapses, providing a much-needed layer of judicial protection for taxpayers acting in good faith.
Understanding the Statutory Context of Penalty Provisions
The core of the dispute rested on the application of Section 270A of the Income Tax Act, 1961. This section governs the penalties for under-reporting and misreporting of income. In the case at hand, the tax authorities argued that because the individual failed to file an original Income Tax Return (ITR) and only disclosed his income after receiving a notice under Section 148, his earnings technically fell under the definition of “under-reported income.”
The Assessing Officer (AO) classified the failure to disclose income as a case of “misreporting,” which carries a heavier penalty burden than simple under-reporting. This classification was based on the premise that the taxpayer had suppressed material facts. However, the legal framework governing these penalties is not absolute. Section 270A(6)(a) provides a crucial exclusion mechanism. It stipulates that an amount shall not be considered under-reported income if the taxpayer provides a bona fide explanation and discloses all material facts necessary to substantiate that explanation. The Jaipur ITAT’s intervention highlights that tax authorities must exercise discretion and consider the intent behind a taxpayer’s actions before imposing punitive measures.
The Intersection of International Mobility and Tax Compliance
The migration of professionals from India to overseas markets, such as the United States, involves significant administrative and logistical pressure. For many, managing dual tax residency, understanding the Double Taxation Avoidance Agreement (DTAA) provisions, and ensuring compliance with local Indian tax laws simultaneously can lead to inadvertent oversights.
In the case decided by the ITAT, the taxpayer’s failure to file his ITR was triggered by the life-altering transition of moving abroad. While the law mandates strict adherence to deadlines, the tribunal acknowledged that such a lapse, when isolated, does not automatically equate to tax avoidance. The taxpayer’s previous history of consistent, timely filings played a pivotal role in the tribunal’s decision. This serves as a significant insight for the Indian business community: maintaining a clean, consistent tax history acts as a secondary defense mechanism should a procedural error occur during a period of transition.
The Role of Voluntary Disclosure and Proactive Correction
A defining feature of this case was the taxpayer’s proactive effort to rectify his status. Long before the Income Tax Department initiated reassessment proceedings, the individual voluntarily paid the self-assessment tax, including the applicable interest and late fees. This demonstrated a clear intent to comply with the law rather than evade it.
For many taxpayers, the fear of legal repercussions often leads to paralysis; however, this case demonstrates that voluntary rectification can be a strong mitigating factor. The fact that the taxpayer paid his dues nearly three years before the department issued a formal reopening notice under Section 148 significantly weakened the department’s position. The tribunal recognized that the department’s attempt to levy a penalty for misreporting was disproportionate to the taxpayer’s conduct. For Indian professionals, this reaffirms that if a filing deadline is missed, the most prudent course of action is to settle the outstanding tax liability as soon as possible, rather than waiting for an audit notice.
Judicial Interpretation and the Defense of Bona Fide Intent
The ITAT Jaipur bench, comprising members Annapurna Gupta and Kuldip Singh, performed an essential function by looking beyond the letter of the law to the spirit of it. By invoking the exclusion clause under Section 270A(6), the tribunal prioritized equity. The ruling emphasizes that the tax machinery should not be used to punish honest taxpayers who experience genuine, documentable administrative delays or lapses.
Furthermore, the tribunal’s decision to condone a 49-day delay in filing the appeal shows that the judiciary recognizes the technical limitations of the modern digital tax ecosystem. The taxpayer faced a jurisdictional mismatch on the official portal, a common frustration for many dealing with the complexities of the Income Tax India website. The tribunal’s willingness to accept this technical difficulty as a valid reason for the appeal delay reflects a modern, pragmatic approach to tax administration that acknowledges the difficulties taxpayers face when interacting with centralized government platforms.
Strategic Takeaways for Taxpayers and Practitioners
This ruling serves as a blueprint for tax practitioners handling similar cases. When challenging penalties, the focus should not merely be on the technical definitions of under-reporting, but on the “bona fide” nature of the taxpayer’s explanation. Practitioners must compile a comprehensive narrative that includes:
1. A clear timeline of the events leading to the lapse, highlighting external factors like international relocation.
2. Evidence of past compliance to establish the taxpayer’s record of good faith.
3. Proof of voluntary payment of taxes and interest prior to any coercive action by the tax department.
4. Detailed documentation of any technical difficulties encountered during the filing process, particularly when dealing with system-related glitches.
For the broader market, this case highlights that the Income Tax Department’s automated notices—generated based on data discrepancies—often lack the nuance required to distinguish between tax evasion and human error. As the department shifts further toward technology-driven scrutiny, taxpayers must remain vigilant and ensure their records are meticulously maintained to defend against automated penalties.
In conclusion, the ITAT Jaipur verdict is a win for common sense in tax jurisprudence. It reinforces the principle that while tax compliance is non-negotiable, the penalty framework is designed to curb deliberate fraud, not to penalize the accidental oversights of honest, mobile professionals. As the Indian economy becomes increasingly globalized, tax laws must continue to evolve in a way that remains firm against evasion while remaining accessible and fair to the vast majority of taxpayers who strive to contribute to the national exchequer.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News