The Great AI Correction: Dissecting the Recent Market Volatility
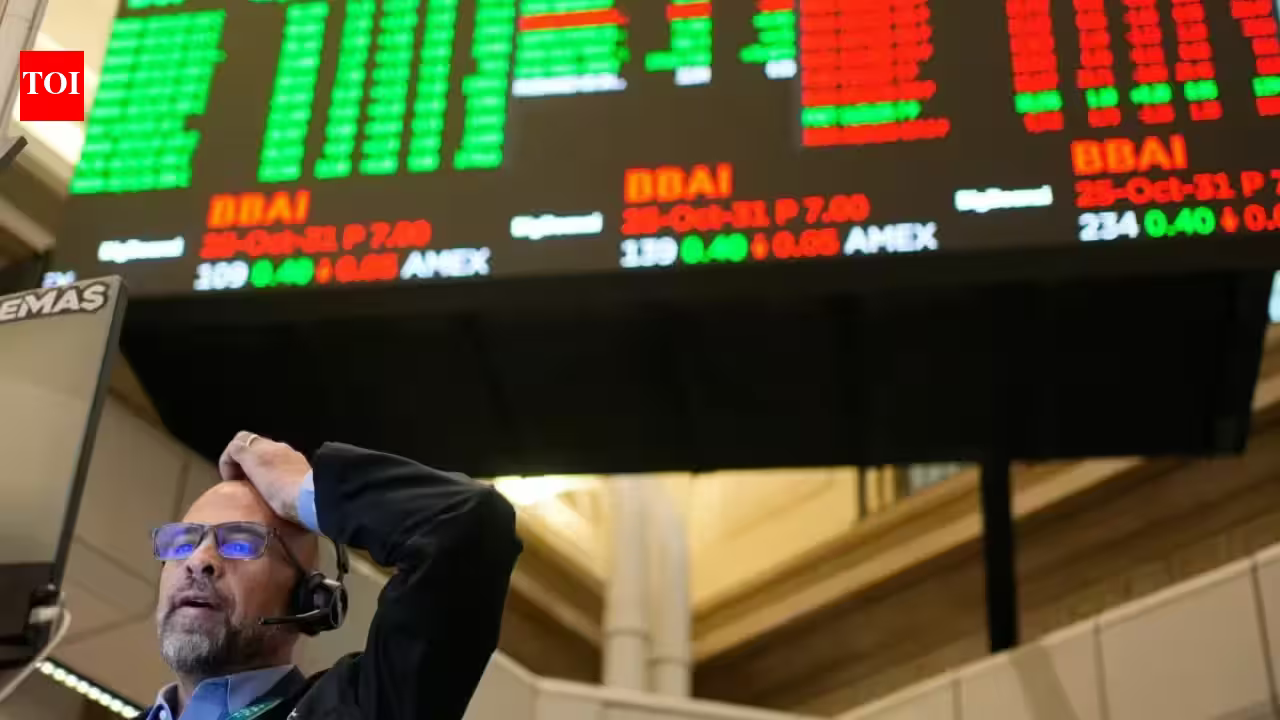
The recent turbulence in global financial markets, characterized by a sharp sell-off in technology and artificial intelligence (AI) stocks, represents a significant inflection point for investors. As the S&P 500 slipped into correction territory—defined as a decline of 10 percent or more from recent peaks—and the Nasdaq Composite retreated into negative territory for the year, the financial landscape has shifted from aggressive optimism to cautious defensiveness. This correction is not merely a technical adjustment; it is a fundamental reassessment of the valuation metrics that have driven global markets for the better part of two years.
For years, the promise of generative AI and the massive capital expenditure fueling data center expansion have acted as a buoyancy mechanism for the broader market. When industry giants like Nvidia, AMD, and Micron lead the way, the “AI trade” was perceived as the primary engine of secular growth. However, when the Philadelphia Semiconductor Index experiences a double-digit decline in a single session, it signals that the market is beginning to prioritize near-term cash flows over long-term technological potential. The current phase reflects a transition where investors are demanding tangible proof of earnings growth to support high price-to-earnings multiples.
Evaluating the Catalyst for the Semiconductor Sell-off
The epicenter of the current volatility lies within the chipmaking sector. Companies that were once the darlings of the stock market are now facing intense scrutiny. The 14 percent drop in Nvidia shares, exacerbated by ongoing concerns regarding accounting investigations and complex international supply chain dealings, serves as a case study in how idiosyncratic risks can amplify systematic downturns. When high-growth sectors face both macroeconomic headwinds—such as rising borrowing costs—and company-specific regulatory challenges, the result is a rapid repricing of risk.
Beyond Nvidia, the broader semiconductor industry is grappling with the law of large numbers. The sheer scale of spending on data centers has reached a level where institutional investors are questioning the sustainability of capital expenditure. If the revenue generated by downstream AI applications fails to keep pace with the massive infrastructure costs incurred by cloud providers and chipmakers, margins will inevitably compress. This skepticism is further compounded by geopolitical trade restrictions, which continue to complicate the export landscape for advanced computing hardware, particularly regarding markets in Asia.
The Ripple Effect: Global Market Contagion
The sell-off has not been confined to US borders; it has triggered a synchronized downturn across global exchanges. The steep declines in Japan’s Nikkei, South Korea’s Kospi, and Taiwan’s stock market illustrate the deep integration of the global technology supply chain. These markets are heavily exposed to the fluctuations of the semiconductor industry, as they host many of the primary foundries and component manufacturers that feed the global AI ecosystem.
Taiwan’s market, in particular, suffered its largest weekly decline since 1990, highlighting the disproportionate impact of technology-heavy indices during periods of sectoral rotation. When capital flees from high-risk growth assets, it creates a liquidity vacuum that affects all interconnected regions. For global investors, the current environment serves as a reminder that diversification is effective only if assets do not exhibit high correlation during stress events. In this instance, the global appetite for risk has retracted simultaneously, pushing investors toward the traditional safety of US government bonds, as evidenced by the rally in Treasuries and the subsequent decline in yields.
Implications for the Indian Business Ecosystem
The Indian market, while historically more focused on domestic consumption and diversified industrial growth, remains sensitive to global liquidity flows. As foreign institutional investors (FIIs) reassess their global portfolios in response to US market corrections, the Indian equity markets often experience secondary shocks through the repatriation of capital. Large-cap technology firms in India, which provide IT services and digital transformation support to global corporations, may face cautious spending patterns from their US-based clients as those firms tighten budgets to navigate their own correction phases.
Furthermore, the Indian manufacturing sector, currently undergoing a push to establish a domestic semiconductor ecosystem, faces a complex environment. A global correction in chip valuations might lead to increased scrutiny from venture capital and private equity investors. Projects that relied on favorable exit valuations or high-growth forecasts may now need to justify their existence based on operational efficiency and domestic demand metrics rather than global sentiment. However, if the correction leads to a rationalization of hardware prices and a stabilization of the global supply chain, it could provide a long-term benefit for Indian firms seeking to integrate into the global electronics value chain at more sustainable entry points.
Navigating the Defensive Shift
As markets enter a defensive phase, the investment narrative is pivoting toward corporate profitability and manageable debt profiles. The decline in gold and silver prices alongside stocks suggests that investors are not merely moving toward safe-haven assets, but are actively liquidating positions to cover margins or manage liquidity. This behavior characterizes a period of forced deleveraging, where the primary objective is capital preservation.
The underwhelming performance of recent market debuts, such as the volatility seen in Anthropic’s stock, reinforces the trend that the “IPO premium” is shrinking. Investors are no longer willing to pay a premium for speculative growth narratives in the absence of a proven, scalable path to profitability. The shift toward higher Treasury yields in recent months has altered the discount rates applied to future earnings, making long-term growth stories inherently less attractive than they were during the era of ultra-low interest rates.
Strategic Outlook for Investors
Looking ahead, the market is likely to undergo a period of consolidation. The “AI correction” is a necessary process of weeding out unsustainable valuations and forcing companies to demonstrate fiscal discipline. While the volatility is unsettling, it provides a clearer picture of which technological advancements possess genuine economic utility versus those driven primarily by hype.
For the savvy investor, this period requires a shift in focus. Attention should be directed toward companies with strong balance sheets, healthy free cash flow, and a clear ability to pass on costs to consumers without sacrificing demand. The era of blind faith in AI-related growth is waning, replaced by a more rigorous assessment of the business fundamentals. While the short-term outlook remains cautious, history suggests that corrections are the mechanism through which markets eventually find their footing, separating transient market fervor from enduring corporate value. The coming months will be defined by how quickly the technology sector can reconcile its ambitious spending plans with the realities of a more restrictive global monetary environment.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News