Australian banking customers and businesses are bracing for significant shifts in the payments landscape as a major Reserve Bank of Australia (RBA) reform arrives on October 1. The legislative change, which bans businesses from applying electronic payment surcharges, is triggering a domino effect across the financial sector, leading to slashed rewards programs and altered fee structures.
### The End of Traditional Rewards
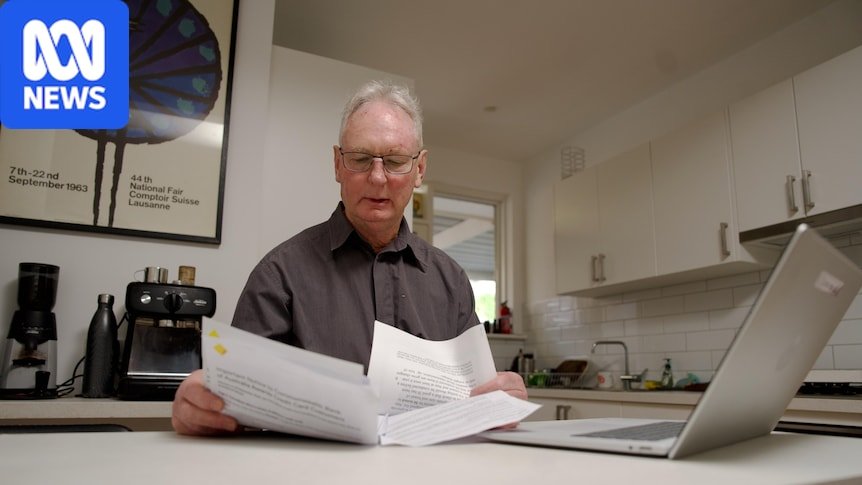
For long-term banking clients like Trevor Vienet, the policy shift has already signaled the end of a decades-long relationship with the Commonwealth Bank (CBA). In anticipation of the RBA’s move to restrict bank revenue—specifically by lowering interchange fee caps from 0.8 per cent to 0.3 per cent—CBA has moved to exit its partnership with the Qantas Frequent Flyer program.
This trend is not isolated to a single institution. Major Australian banks are proactively recalibrating their business models to mitigate the estimated $910 million annual reduction in transaction fee income. As banks move to recoup these losses, many are cutting travel insurance inclusions, raising credit card fees, and rolling out proprietary, more restrictive in-house rewards schemes that often exclude long-term legacy customers.
### Small Business Hurdles and Pricing Pressures
While the RBA estimates the surcharge ban will save consumers roughly $1.6 billion annually, small business owners are sounding the alarm. Operators, such as local swim school owners and hospitality businesses, face the difficult choice of either absorbing the increased processing costs or passing them directly to consumers via higher prices.
Industry experts note that for many small businesses, the transition is far more complex than a simple price hike. For large entities like local councils, which manage millions of dollars in transaction fees, changing pricing structures involves cumbersome, multi-month public consultation processes. Consequently, some businesses are considering drastic measures, such as moving to “cash-only” models or ceasing acceptance of certain credit card brands altogether, which could paradoxically reduce payment options for consumers.
### A Pivot Toward Tech-Driven Alternatives
The regulatory upheaval is acting as a catalyst for a “strategic reset” in how Australians pay for goods and services. Industry analysts are highlighting the untapped potential of Account-to-Account (A2A) payments. By leveraging real-time payment infrastructure, A2A transfers allow money to move directly between bank accounts, bypassing the traditional card networks—such as Visa and Mastercard—that have historically driven the interchange fee economy.
Despite having the necessary infrastructure in place for years, A2A payments have struggled to gain mainstream adoption, representing only a small fraction of current e-commerce and in-store transactions. However, tech-forward payment providers and fintech firms are now positioning these solutions as the logical evolution of the Australian payment ecosystem. As the industry moves past the October 1 deadline, the focus is expected to shift toward integrated platforms that prioritize payment choice, hoping to incentivize both merchants and consumers to embrace digital alternatives that reduce reliance on high-fee card networks.
While the RBA maintains that these changes will not have a long-term inflationary impact, the transition period is proving testing. As businesses scramble to update their point-of-sale systems and customers weigh the value of their now-diminished reward cards, the Australian economy is undergoing a fundamental shift in how the cost of convenience is accounted for at the register.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News