


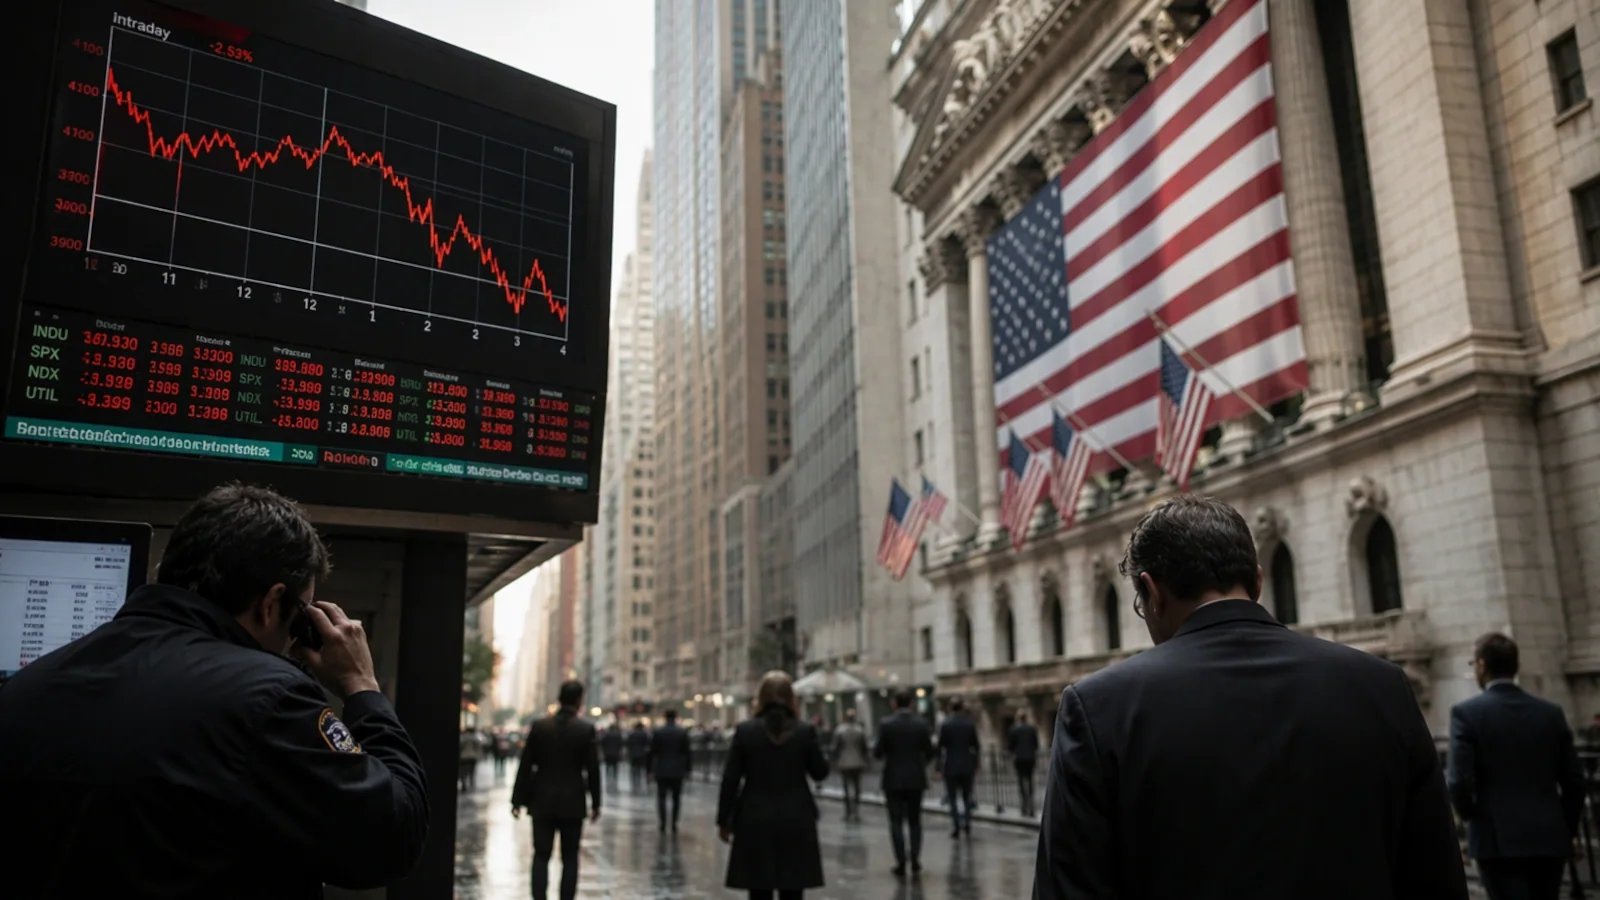
Wall Street experienced a dramatic reversal of fortunes this week, as an intense post-election rally evaporated into a broad-based market sell-off. After initial optimism following the US midterm elections—which saw the Democratic Party secure control of both the House and the Senate—investors abruptly pivoted to a defensive stance. The Nasdaq Composite bore the brunt of the downturn, plummeting 5.52% on November 5 in its most significant single-day decline in over 19 months.
The volatility serves as a stark reminder of the fragile sentiment currently governing the technology sector, particularly regarding the hyper-growth narrative surrounding artificial intelligence and semiconductor manufacturing.
The AI Correction and Valuation Fears
The sell-off was primarily driven by a sharp contraction in AI-linked equities and chipmakers, which have been the primary engines of market growth over the past year. High-profile names suffered substantial losses: AMD and Micron Technology both tumbled by over 17%, while Nvidia experienced a 9.3% drop—its steepest decline since early 2025.
Investors, who had spent the better part of a year pouring capital into the promise of AI infrastructure, data centers, and advanced computing power, suddenly began to question if these assets had become overvalued. The abrupt pullback suggests a “reality check” in the market, where lofty long-term expectations are being weighed against the immediate, tangible risks of massive infrastructure spending. With chipmakers facing tightening margins and shifting sales forecasts—exemplified by Qualcomm’s disappointing guidance on smartphone components—the market appears to be cooling off from its relentless sprint toward an AI-dominated future.
Political Headwinds for Infrastructure
Beyond market technicals, the political landscape is introducing new variables for the tech industry. The sweeping Democratic victory has brought renewed scrutiny to the AI boom. During the campaign, several successful candidates highlighted the environmental and economic costs associated with the rapid expansion of massive data centers, specifically citing concerns over local power grid strain and exorbitant electricity consumption.
This shift has created a climate of regulatory uncertainty. Tech giants and data center operators are now facing questions about whether future federal policies will impose stricter oversight, permit delays, or even limitations on how quickly new AI infrastructure can be built. Because the profitability of the entire AI ecosystem—from server manufacturers to the silicon giants—is predicated on the constant scaling of physical data infrastructure, any hint of legislative interference acts as a catalyst for investor anxiety. The market is currently reassessing whether the “AI gold rush” will face significant bureaucratic obstacles in the coming years.
Profit-Taking Amidst Market Volatility
The speed of the reversal highlights the opportunistic nature of the current trading environment. The market had surged on November 4, with the Dow Jones Industrial Average jumping over 1,000 points as the election results provided a semblance of political clarity. However, this relief rally proved to be a convenient exit point for many institutional investors.
As soon as signs of weakness appeared in the tech sector, the selling pressure became contagious. Traders who had moved into positions ahead of the election began aggressively locking in gains, turning the previous day’s exuberance into a downward spiral. The volatility gauge surged as the sell-off spread from the high-flying tech names to the broader index, illustrating that while markets may cheer political outcomes in the short term, they remain deeply sensitive to valuation concerns and sector-specific risks. As the dust settles, Wall Street is forced to consider a new reality where political headwinds and valuation fatigue may temper the breakneck pace of AI-driven market appreciation.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News