Navigating Capital Gains Tax: Lessons from the Panchkula Tribunal Ruling
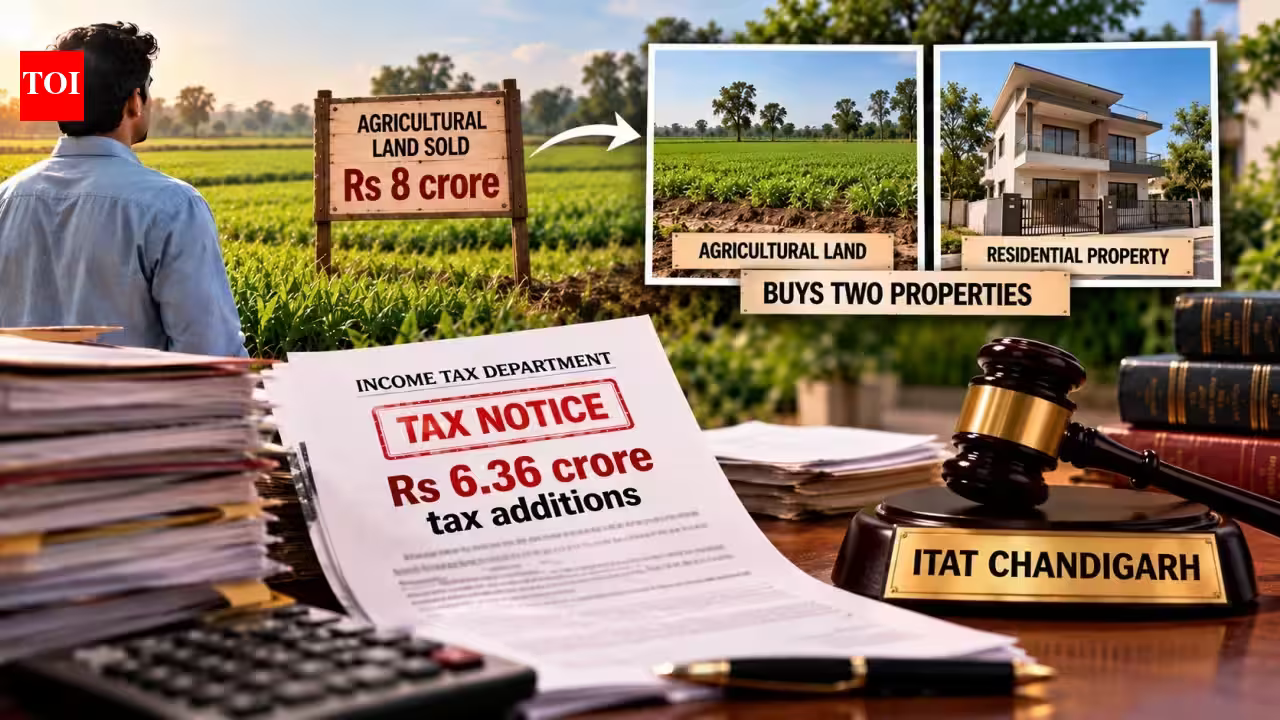
In the complex landscape of Indian taxation, the sale of ancestral assets—particularly agricultural land—often triggers significant capital gains tax obligations. For many taxpayers, the path to compliance involves leveraging specific sections of the Income-tax Act to reinvest proceeds into new assets. However, as demonstrated by a recent ruling from the Income Tax Appellate Tribunal (ITAT) in Chandigarh, the line between permissible tax planning and liability is thin. The case of a Panchkula resident who successfully challenged a Rs 6.36 crore tax addition serves as a critical case study for high-net-worth individuals and landowners regarding the necessity of factual accuracy and the importance of property classification under tax law.
The dispute arose when a taxpayer sold ancestral agricultural land for Rs 8 crore and sought to mitigate his long-term capital gains (LTCG) tax liability by claiming exemptions under Sections 54B and 54F of the Income-tax Act. The Assessing Officer (AO) initially rejected these claims, citing insufficient documentation and questioning the status of the taxpayer’s existing properties. The subsequent legal journey through the Commissioner of Income Tax (Appeals) and finally the ITAT highlights how administrative assumptions—such as misclassifying a commercial asset as a residential one—can lead to severe financial consequences for the assessee.
Decoding Section 54B and Section 54F Exemptions
To understand the stakes of this case, one must appreciate the specific mandates of the Income-tax Act. Section 54B is designed to support the agricultural sector by allowing taxpayers to exempt capital gains earned from the sale of land that was utilized for agricultural activity for at least two years prior to the date of transfer. The primary condition is that the taxpayer must reinvest the gains into new agricultural land within a stipulated period.
Conversely, Section 54F provides a mechanism for taxpayers who sell a long-term capital asset (other than a residential house) to reinvest the net sale proceeds into a residential property. A fundamental constraint of Section 54F is that the taxpayer must not own more than one residential house at the time of the transfer. It is precisely this “residential house” clause that frequently acts as a trap for taxpayers. In the Panchkula case, tax authorities attempted to disqualify the taxpayer by asserting he already owned a property that functioned as a second residence, thereby violating the restriction under Section 54F.
The Role of Factual Verification in Tax Disputes
The pivotal moment in this legal battle was the decision by the ITAT Chandigarh to order a physical inspection of the disputed property in Dhakoli, Zirakpur. The Income Tax Department had initially treated this property as a residential house, which would have rendered the taxpayer ineligible for the 54F exemption. However, the taxpayer maintained that the property was utilized for commercial purposes, housing both an office and a restaurant.
This highlights a recurring issue in Indian tax audits: the reliance on paper-based classification versus the ground reality of asset utilization. The ITAT’s intervention—directing the AO to conduct an on-ground verification—shifted the discourse from theoretical assumptions to empirical evidence. The resulting remand report confirmed that the property was indeed located in a commercial zone and served a commercial purpose. By establishing that the asset was not a residential house, the tribunal effectively dismantled the primary argument used by the tax authorities to deny the exemption. This underscores a vital takeaway for taxpayers: when claiming exemptions based on the nature of a property, maintaining clear documentation regarding usage—such as trade licenses, utility bills, or municipal records—is as important as the sale deed itself.
The Urbanization Debate and Section 54B Eligibility
The case also brought to the fore the nuances of Section 54B, particularly regarding the geographical location of replacement land. The Income Tax Department challenged the taxpayer’s purchase of new land, arguing that because the new properties were located in an urban area, they might not qualify for the intended relief.
The tribunal’s decision to reject this objection provides a layer of protection for landowners navigating the rapid urbanization of Indian outskirts. The ITAT ruled that the mere location of agricultural land in an urban area does not automatically invalidate a claim under Section 54B. Provided the taxpayer can substantiate the acquisition of land for agricultural purposes through valid purchase deeds and prove that the sale proceeds were indeed funneled into these investments, the location itself is secondary to the productive use of the land. This clarification is particularly relevant given the rapid expansion of city limits across states like Punjab and Haryana, where the distinction between rural and urban land often blurs over time.
Strategic Compliance for Future Asset Sales
The ITAT Chandigarh ruling serves as a reminder that the Income Tax Department’s scrutiny of capital gains is rigorous and data-driven. As the regulatory environment shifts under new legislative frameworks, such as the Income-tax Act, 2025, the burden of proof rests heavily on the taxpayer to demonstrate both eligibility and compliance.
For those planning to dispose of large assets, several strategic lessons emerge from this outcome:
First, maintain a clear, chronological trail of evidence. In this instance, the production of purchase deeds for the new agricultural properties allowed the tribunal to quantify the exact deduction amount. Without such precise documentation, the tribunal would have struggled to grant relief even if the underlying logic favored the taxpayer.
Second, understand the classification of all existing real estate assets. The dispute over the Zirakpur property demonstrates that the tax department’s initial categorization may not always align with the actual usage. Taxpayers must proactively ensure that their property records—such as municipal tax classifications or commercial usage certificates—accurately reflect how the property is currently used to avoid being blindsided during an audit.
Third, engage professional tax advisors early in the transaction process. The complexity of balancing multiple exemptions while adhering to ownership restrictions under Section 54F requires careful planning. As the Chandigarh tribunal demonstrated, the court is willing to look beyond initial assessments, but this requires a robust defense rooted in facts and verified evidence.
Concluding Thoughts
The victory for the Panchkula taxpayer is not merely a win against a tax demand; it is a validation of the importance of granular, evidence-based tax compliance. By successfully challenging the arbitrary classification of his commercial asset and defending the agricultural status of his new investments, the taxpayer prevented a substantial financial loss.
As the Indian economy continues to see massive capital appreciation in real estate, the intersection of property ownership and tax law will remain a high-stakes area. Taxpayers must move away from generic assumptions regarding tax exemptions and instead adopt a meticulous approach to documenting the nature and usage of every asset in their portfolio. When backed by verifiable facts, the law provides sufficient avenues to reinvest capital effectively; without that backing, however, even legitimate claims risk being disallowed in the face of bureaucratic scrutiny. The Chandigarh ITAT ruling is a powerful precedent, reinforcing that in the eyes of the law, the substance of property usage must always take precedence over external labels or assumptions.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News