The Anatomy of the Q3 2026 PC Market Contraction
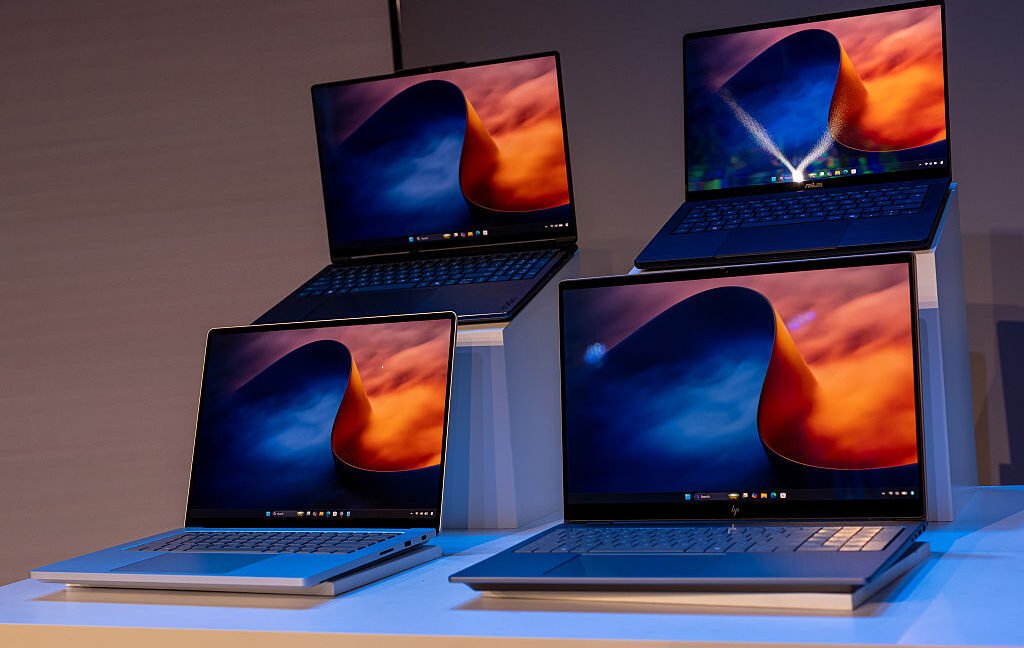
The global personal computing landscape is currently navigating a period of significant turbulence. Recent data from market intelligence firms Omdia and IDC confirm a dramatic downturn in global hardware distribution for the third quarter of 2026. According to Omdia, global shipments of laptops, desktops, and workstations plummeted by 21.2 percent year over year, settling at 58.1 million units. This marks the most severe decline the industry has witnessed since the first quarter of 2023.
The breakdown by device category reveals the breadth of this slump. Desktop computers, including dedicated workstations, saw shipments fall by 23.5 percent to 11.7 million units. Laptops and portable workstations fared slightly better in absolute volume but still experienced a significant decline of 20.6 percent, totaling 46.4 million units. These figures highlight a systemic cooling of hardware demand across all professional and consumer sectors.
IDC Perspectives on Historical Declines
Corroborating the Omdia data, IDC reports a similarly stark 20.1 percent year-over-year contraction, with total shipments falling to 62.7 million units from 78.5 million in the third quarter of 2025. This contraction is particularly jarring because the third quarter typically acts as a seasonal growth period, often outperforming the second quarter. In 2026, however, the industry moved in the opposite direction, shipping 9.1 percent fewer units than the 68.2 million recorded in the second quarter.
Jitesh Ubrani, research director for consumer devices at IDC, notes that while this is the steepest third-quarter decline in the firm’s tracking history, it should be viewed in the context of recent market volatility. Periods such as the final quarter of 2022 and the first quarter of 2023 saw even deeper drops, though those were largely characterized as corrections following the unprecedented demand spikes during the pandemic era. The current 2026 downturn appears driven by different, more localized economic factors within the supply chain.
Inventory Overhang and Supply Chain Dynamics
A primary driver behind this sudden contraction is a strategic miscalculation regarding component costs. Earlier in 2026, PC vendors and sales channels anticipated a significant rise in memory prices. In response, many manufacturers aggressively increased their order volumes to secure hardware components at lower rates before the expected hike. This surge in procurement effectively front-loaded supply, leading to a surplus of inventory sitting in distribution centers and retail channels by the time the third quarter arrived.
As these channels began the third quarter with high stock levels, they found themselves burdened with excess inventory. When end-user demand failed to accelerate, these vendors were forced to throttle new orders to prevent further accumulation of unsold stock. This buildup is now exerting a negative pressure on shipment figures, as retailers prioritize clearing their existing shelves rather than acquiring the latest iterations of desktop and laptop systems.
Impact of Pricing on Consumer Demand
The broader economic environment continues to play a critical role in cooling the market. High retail prices are cited as a key factor in suppressing consumer and enterprise demand. With the cost of essential components and labor remaining elevated, the final sticker price for modern computing hardware has climbed. Potential buyers, facing economic uncertainty or prioritizing other capital expenditures, are delaying upgrades to their existing fleets.
When hardware becomes more expensive without a proportional increase in perceived utility or performance for the average user, the replacement cycle naturally lengthens. Corporations are particularly cautious, extending the life of their laptop fleets by another twelve to twenty-four months rather than initiating standard refresh cycles. This “wait-and-see” approach among large enterprise customers contributes significantly to the stagnant volume numbers reported by industry analysts.
Future Outlook and Market Stabilization
Looking toward the remainder of the year and into 2027, the industry faces the challenge of rebalancing supply with realistic demand metrics. The current inventory glut will likely take several quarters to normalize, meaning that manufacturers will remain cautious with their production targets. The emphasis for PC vendors will likely shift from aggressive volume expansion to inventory management and profitability stabilization.
For the enterprise sector, the focus remains on integrating hardware that supports specific software-driven efficiencies, such as enhanced security, better power efficiency, and compatibility with modern collaboration tools. While the Q3 figures are historically poor, they represent a transition phase for the industry. Once the excess stock currently clogging the distribution channels is absorbed, the market is expected to stabilize at a baseline level that reflects current technological requirements rather than the distorted cycles of recent years. The industry’s ability to navigate this period will depend on how quickly vendors can align their production schedules with the reality of more conservative consumer spending habits.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News