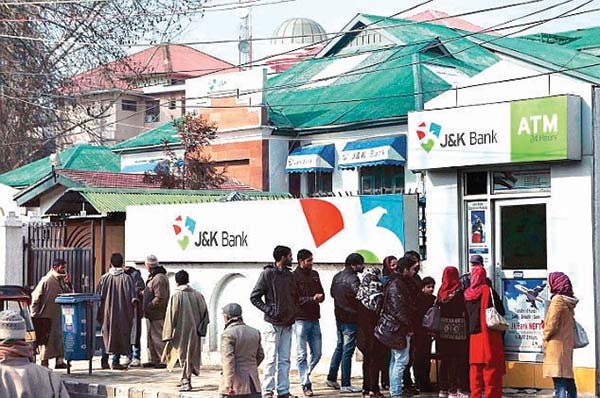
Jammu and Kashmir Bank is facing a significant erosion of its long-standing competitive advantage as its “cheap money” deposit base continues to shrink. Over the last 12 quarters, the bank’s Current and Savings Account (CASA) ratio has plummeted from 50.59% in December 2023 to 42.01% as of September 2026, squeezing profit margins and raising questions about the sustainability of its current growth strategy.
Provisional numbers released on October 3 show that while total deposits rose 16.3% to Rs 1,76,796 crore and gross advances grew by 23.7%, the bank is increasingly reliant on expensive term deposits to fuel its expansion. This shift has triggered a steady decline in Net Interest Margins (NIM), which have fallen from a peak of 4.04% to 3.28%—the lowest level in nearly three years and well below the 3.5% target set by management earlier this year.
Historically, J&K Bank benefited from a captive, government-backed deposit pool that allowed it to operate with lower funding costs than its private and public sector peers. However, the latest data suggests that this structural advantage is leaking away. While the bank’s CASA ratio remains above the industry average of 39%, the trend is persistently downward, with the ratio falling in nine of the last 11 quarters.
The decline is largely attributed to a structural shift in household savings toward mutual funds and higher-yielding assets, compounded by the bank’s own inability to keep pace with the digital transformation of the banking sector. A local banker noted that the younger generation is increasingly favoring more tech-forward lenders, leaving J&K Bank struggling to retain its once-loyal customer base.
The reliance on costlier term deposits is stark: between December 2023 and September 2026, the bank added Rs 48,254 crore in new deposits, but less than 20% of that inflow was in the form of low-cost CASA funds. Term deposits have surged 61% over the period, significantly outpacing the 14% growth in CASA balances.
This funding mix shift has created an “asymmetry” in how the bank re-prices its assets and liabilities. While the loan book, often linked to external benchmarks, re-prices rapidly in response to market conditions, the deposit book has become increasingly dominated by slow-moving, high-cost term deposits. This imbalance has contributed directly to the sustained pressure on margins.
Management has repeatedly revised its internal targets downward as they have consistently failed to materialize. Past promises of stabilizing CASA at 50%—and later 48%—have been abandoned in favor of more modest goals, yet even these adjusted benchmarks are proving difficult to hold.
Despite these concerns, the bank remains financially robust, boasting its best asset quality in years with gross non-performing assets at 2.37% and a strong capital adequacy ratio. However, the fundamental challenge remains: the cheap capital that defined J&K Bank’s unique market position is no longer growing fast enough to fund its ambitions, forcing the lender into a high-cost competitive arena that is rapidly diluting its traditional profitability.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News