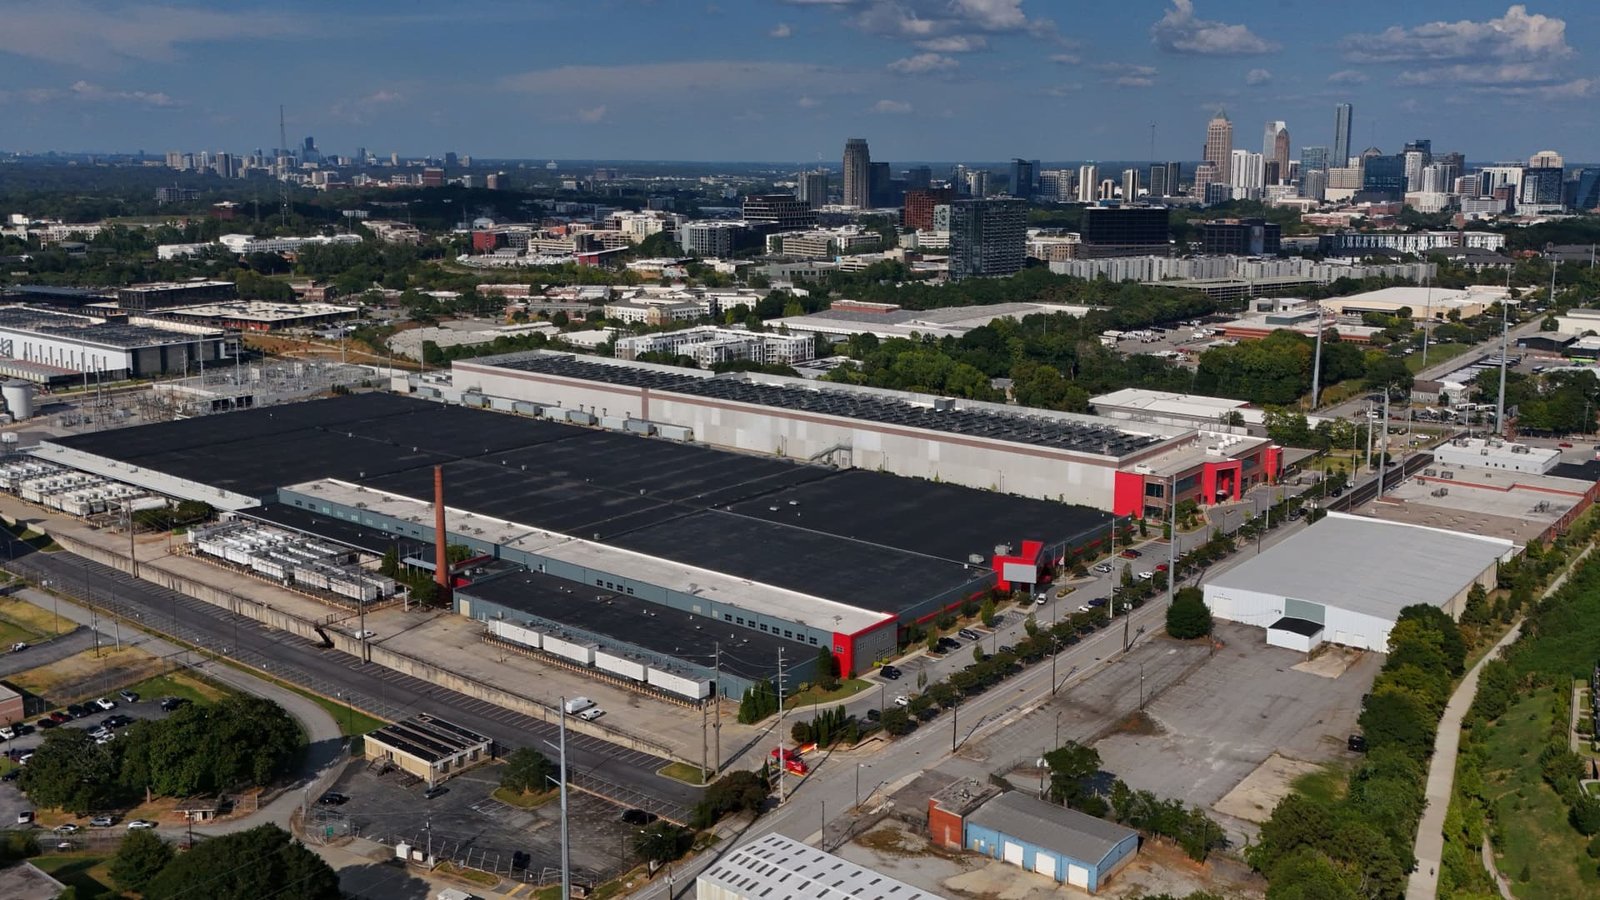
Tech giants are currently engaged in a massive, multi-trillion-dollar gamble, funneling record amounts of capital into AI infrastructure in hopes of securing dominance in the next era of computing. However, the latest round of earnings reports has revealed a growing friction between these aggressive long-term ambitions and the current performance of their legacy revenue engines.
As of the most recent quarter, the financial strain is becoming impossible to ignore. Meta, Alphabet, and Amazon have all reported negative free cash flow, relying heavily on existing balance sheets to fuel their hardware and data center acquisitions. Microsoft remains the only major hyperscaler to maintain positive cash flow, though its own liquidity has dropped 27% as it prepares to enter the bond market to sustain its AI-driven capital expenditure.
## The Cost of the AI Arms Race
The scale of spending is unprecedented. Amazon, for instance, is projected to spend $220 billion on capital expenditures this year alone, with analysts anticipating that figure could climb toward $280 billion in 2027. Meta is similarly constrained, forecasting up to $145 billion in annual spending, with expectations for that number to surge past $210 billion by 2027.
These massive outflows have triggered a nervous reaction from Wall Street. Alphabet’s recent earnings saw its stock price suffer its steepest decline in company history. Investors are increasingly wary of a model where future AI promises must be financed by stagnant core businesses. While some analysts argue that these companies have the operational history to justify this “borrowing from the present,” others fear that AI infrastructure spending is ballooning faster than the revenue generated by the businesses meant to support it.
## Cracks in the Core Business
The core products that once provided reliable, predictable growth are showing signs of vulnerability. Alphabet, in particular, is facing mounting pressure as its search engine business experiences three consecutive quarters of slowing growth. This has sparked concerns that AI-powered alternatives—such as ChatGPT or other third-party chatbots—are beginning to displace the search and advertising models that form the backbone of the company’s success.
Amazon is facing similar headwinds, with its retail growth decelerating significantly compared to prior years. Revenue guidance for the company’s crucial holiday quarter fell short of analyst expectations, signaling that the macroeconomic environment is impacting consumer spending, making it harder for the company to absorb its ballooning AI infrastructure costs.
## Investors Divided on Future Utility
There is a sharp divide between those who view this spending spree as a necessary evolution and those who see it as a potential bubble. Skeptics point to the “neocloud” startups that are currently struggling to secure financing, arguing that if interest rates remain high, even the giants could find themselves in a precarious position if their AI services do not quickly become profitable.
Conversely, industry proponents remain optimistic. They argue that companies like Alphabet and Amazon possess deep-rooted revenue streams that smaller competitors lack. To these supporters, the current negative cash flow is not a sign of financial distress, but rather a calculated, responsible investment strategy.
As Amazon CEO Andy Jassy noted during the company’s recent earnings call, the current market climate might not be the most “convenient” time for such a massive industrial shift, but these firms are operating under the belief that the window of opportunity is narrow and demands immediate, heavy investment regardless of the short-term financial discomfort. For now, the tech industry is waiting to see whether these massive infrastructure builds will yield the revolutionary revenue streams they promise or simply result in a long period of margin pressure.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News