The Crisis of Confidence: Analyzing the US Housing Stagnation
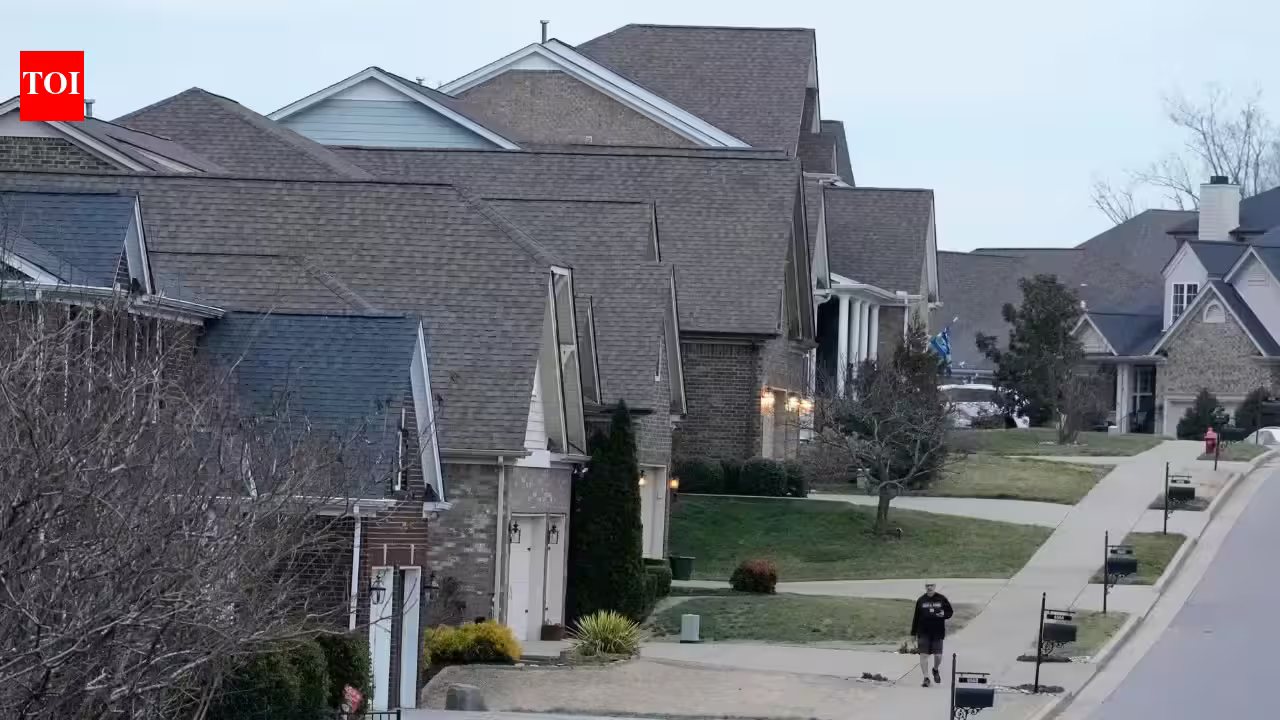
The United States housing market, a critical pillar of the American economy, is currently navigating a period of profound uncertainty. The recent data from the National Association of Home Builders (NAHB)/Wells Fargo Housing Market Index reveals a sobering reality: homebuilder confidence has plummeted to its lowest level in over 14 years. This decline is not merely a statistical fluctuation; it is the culmination of a “perfect storm” of macroeconomic pressures, including persistent inflation, elevated mortgage rates, and supply-side constraints that are forcing builders to re-evaluate their operational strategies.
At its core, this downturn is driven by the interaction between the cost of capital and the cost of production. When mortgage rates approach levels not seen in decades, the immediate effect is a severe contraction in buyer purchasing power. As potential homeowners find themselves priced out of the market, the ripple effect reaches developers who are left with mounting inventories of unsold homes. This inventory overhang, coupled with the rising costs of essential construction inputs such as lumber, steel, and energy-intensive materials, creates a margin squeeze that is increasingly difficult to navigate. The geopolitical tensions, particularly those impacting global energy markets, have only exacerbated these inflationary pressures, keeping borrowing costs high and consumer sentiment subdued.
Structural Constraints and the Labor Supply Deficit
While demand-side factors like mortgage rates dominate the headlines, the supply side of the housing equation remains deeply problematic. The construction industry in the US is currently grappling with a acute labor shortage, a challenge further complicated by shifting immigration dynamics. As noted by industry leaders, enforcement actions and a shrinking pool of available, skilled labor have created significant bottlenecks on active job sites. When projects are delayed due to a lack of personnel, the financial carrying costs for developers escalate, further eroding profitability.
This labor shortage is not occurring in a vacuum. It is compounded by the rising costs of construction financing. Developers are currently borrowing at significantly higher interest rates than in previous years, which means that the time taken to complete a house is directly tied to the project’s internal rate of return. Every day a project remains incomplete due to labor shortages is a day where debt service consumes a larger portion of the projected profit. For many small-to-mid-sized builders, these pressures are existential, leading to a visible trend of abandoning new project starts to mitigate exposure to further financial risk.
The Rise of Concessions and the Pricing Dilemma
To counteract the sharp decline in buyer traffic, builders have turned to aggressive pricing strategies. The data indicates that a significant percentage of builders are now resorting to price cuts and various sales incentives to clear existing inventory. This behavior is a clear indicator of a buyer’s market where the developer has lost the upper hand. By lowering prices or offering mortgage rate buy-downs, developers are essentially cannibalizing their own margins to maintain cash flow.
However, these interventions are a temporary salve for a structural issue. When nearly half of all builders report reducing prices, it signals a systemic lack of alignment between what it costs to build a home and what the average consumer is willing—or able—to pay. This divide creates a “gap of affordability” that is unlikely to be bridged by price cuts alone. As long as the cost of borrowing remains high and the cost of raw materials remains inflated, developers will continue to struggle with maintaining profitability without jeopardizing the quality or viability of their projects.
Indian Real Estate: Parallels and Market Divergence
For stakeholders in the Indian real estate market, the situation in the United States offers both a cautionary tale and a study in market divergence. The Indian housing sector has, for the most part, experienced a period of robust demand, particularly in the premium and mid-segment categories, despite similar global inflationary pressures. Unlike the US, where homeownership is heavily financed through long-term fixed-rate debt, the Indian market functions on a mix of bank financing and personal savings.
While the US market is currently suffering from a “wait and see” approach from buyers, the Indian market has seen a consistent influx of institutional capital and strong end-user demand, particularly in tier-1 cities. However, Indian developers are not immune to the cost pressures seen abroad. Rising commodity prices, such as steel and cement, have put significant strain on project budgets in India as well. The difference lies in the demographic tailwinds; India’s rapid urbanization and the aspiration for homeownership among the expanding middle class serve as a buffer against the kind of stagnation seen in the US.
Nonetheless, Indian developers should closely monitor the US housing crisis as a bellwether for global liquidity conditions. If high interest rates persist globally, Indian lending institutions may eventually pass on these costs to retail borrowers with greater intensity. Furthermore, the reliance on imported construction components in India makes the domestic industry vulnerable to the same global supply chain disruptions that have hampered American builders.
Looking Toward a Period of Market Adjustment
The outlook for the US housing sector remains cautious as we approach the midterm election season. Housing affordability has emerged as a central political theme, yet the solutions—whether they involve deregulation, tax incentives, or monetary policy shifts—remain highly contested. The core of the issue is that housing markets are slow to respond to policy changes. Even if interest rates were to stabilize tomorrow, the backlog in construction and the underlying labor shortages would take years to resolve.
For investors and developers, the message is clear: the period of easy growth in the housing sector is behind us. Success in the current climate requires a shift toward efficiency, strict cost control, and a realistic assessment of buyer demand. The current data from the NAHB indicates that the market is in a recalibration phase. Builders who rely on traditional volume-based strategies will find the going difficult, while those who can innovate—perhaps by optimizing construction technology or focusing on smaller, more cost-effective housing footprints—may be better positioned to weather the storm.
Ultimately, the stagnation in the US housing market serves as a stark reminder of the interconnectedness of modern global finance. When interest rates rise, the dream of homeownership quickly shifts from a viable goal to a financial burden. Whether this period of weakness leads to a prolonged recession in housing or a necessary cooling of inflated valuations will be the defining economic story for the remainder of the decade. For the global business community, it is a reminder that when the foundational element of housing becomes fragile, the repercussions are felt across the entire economic spectrum, from manufacturing to labor markets and beyond.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News