The Strategic Imperative Behind India’s Record LNG Imports
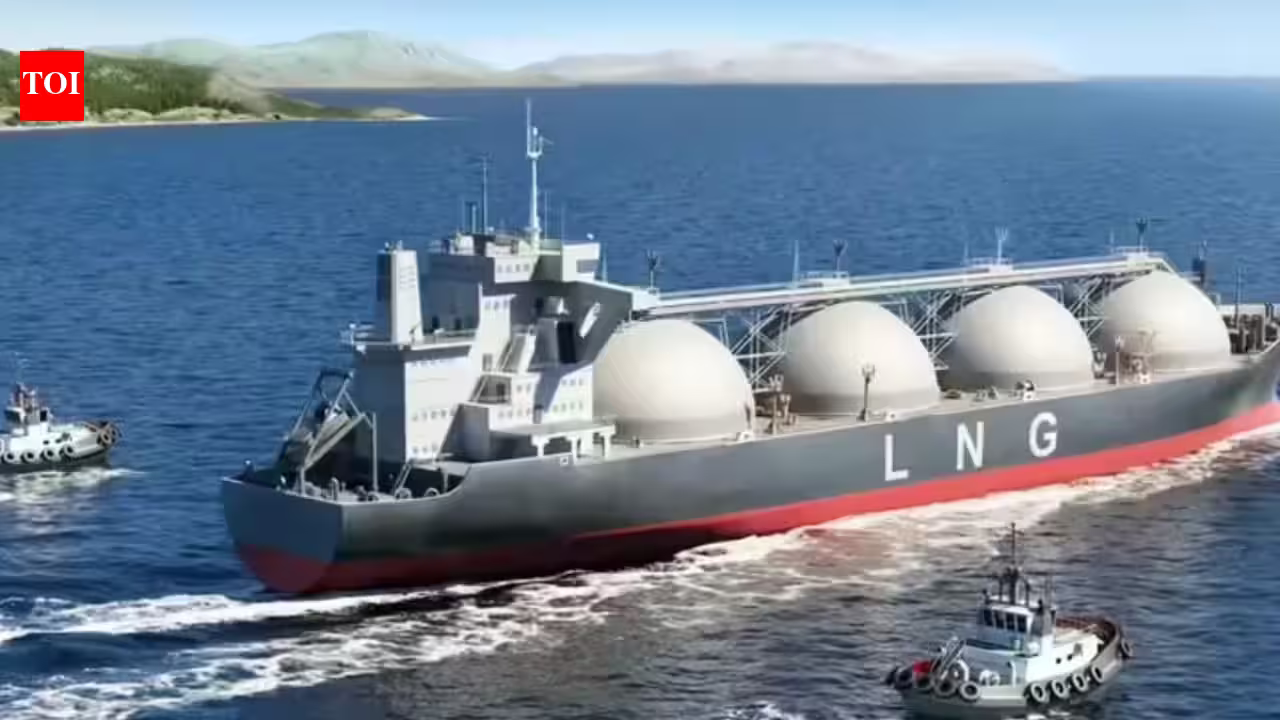
The recent surge in India’s Liquefied Natural Gas (LNG) imports, hitting a record 2.7 million tonnes in October, signals a significant shift in the country’s energy management strategy. As the world’s third-largest energy consumer, India’s reliance on imported hydrocarbons remains a critical variable in its macroeconomic stability. The 17.4% year-on-year increase in LNG imports highlights the country’s deepening integration into the global gas market, driven by industrial necessity rather than discretionary consumption.
This import surge is not merely a consequence of price fluctuations; it represents a tactical response to structural gaps in domestic energy production. With domestic natural gas output plateauing or declining, India’s import dependence has crept upward from 50% to approximately 52%. This trend is expected to persist as the economy scales, necessitating a robust framework for securing long-term supply contracts. The power, fertilizer, and city gas distribution (CGD) sectors are currently the primary drivers of this demand. As India approaches winter, the seasonal decline in solar energy availability necessitates a higher reliance on gas-fired power plants to maintain grid stability and prevent supply deficits.
Geopolitical Resilience and Supply Chain Diversification
A critical insight from recent market data is the recovery of supplies from Qatar, a cornerstone of India’s energy security architecture. For years, Qatar has accounted for 40% to 50% of India’s LNG imports. Earlier disruptions related to maritime security in the Strait of Hormuz had threatened this reliable inflow, forcing Indian energy companies to seek costlier spot market alternatives. The rebound in Qatari shipments—which saw a 370% increase compared to September levels—underscores the efficacy of long-term supply agreements and the deepening diplomatic ties between New Delhi and Doha.
Simultaneously, India has successfully diversified its supplier base. While Qatar remains vital, the United States has solidified its position as a leading provider, contributing 0.6 million tonnes during October. Furthermore, imports from the UAE, Oman, Angola, Nigeria, and Australia demonstrate a conscious effort by Indian state-owned and private players to avoid over-reliance on a single geographic theater. This multi-pronged supply approach is crucial for insulating the Indian market from regional conflicts that frequently destabilize global energy logistics.
The Interplay Between Power Generation and Industrial Feedstock
The industrial sector in India acts as the primary engine for gas consumption. The fertilizer industry, essential for maintaining agricultural productivity, requires natural gas as a critical feedstock for ammonia production. As domestic fertilizer plants aim to meet the requirements of the next crop cycle, their demand for gas remains inelastic. When combined with the seasonal pivot of power utilities—which increase their gas burn to compensate for lower solar generation during the winter months—the cumulative demand creates a formidable upward pressure on import volumes.
This seasonal dependency creates unique challenges for gas procurement planning. Utility providers must balance the high costs of spot-market LNG against the requirement for uninterrupted power supply. Given that India’s power demand continues to grow in tandem with its GDP, the government is likely to prioritize policies that enhance storage capacity and infrastructure at regasification terminals. The current reliance on imports necessitates that these terminals operate at peak efficiency to prevent bottlenecks in the supply chain, particularly when global freight costs remain volatile.
Crude Oil Dynamics and the Russian Supply Equation
While LNG captures the spotlight for its recent record-breaking performance, the crude oil landscape remains equally significant. India’s crude imports reaching 5.6 million barrels per day (mbd) reflects an industrial sector running at high capacity. Despite fluctuations in supply volumes, Russia has retained its position as the largest supplier to India, accounting for roughly 36% of total imports. This relationship, established following global geopolitical shifts in 2022, has provided Indian refiners with critical cost efficiencies.
However, the market is currently witnessing a realignment. Analysts have noted that the delivered-price advantage of Russian crude is being gradually eroded by rising freight costs. When the cost of insurance and long-haul shipping for Russian barrels rises, the competitive edge diminishes, allowing refiners to reconsider supplies from the Atlantic Basin and West Asia. The resurgence of supply flows from Saudi Arabia and Iraq suggests that the Indian refining sector is highly sensitive to total landed costs rather than base prices alone. This arbitrage behavior demonstrates a sophisticated procurement strategy that leverages global market conditions to optimize refining margins.
The Future Outlook for India’s Energy Security
Looking ahead, India’s path toward energy security will likely involve a dual approach: expanding renewable energy capacity while securing reliable, long-term gas contracts. The current reliance on imported gas is a transitional necessity, yet it serves as a critical bridge. As the government continues to push for a gas-based economy to reduce the carbon intensity of its industrial output, the demand for LNG is projected to grow linearly.
Infrastructure development, including the expansion of the National Gas Grid and the commissioning of new LNG regasification facilities, will be the key to managing this demand. Policymakers are also tasked with the delicate balance of keeping energy prices affordable for domestic consumers while ensuring that import costs do not spiral, which would otherwise threaten the current account deficit. As maritime intelligence continues to evolve, Indian companies are likely to use sophisticated data analytics to forecast demand and optimize their shipping logistics, further refining their ability to navigate global supply shocks.
In conclusion, the record LNG and crude import figures for October illustrate a robust, demand-driven economy that is successfully managing the complexities of a volatile global energy market. Through a combination of strategic partnerships, active supply chain diversification, and proactive consumption management, India is effectively securing the resources required to sustain its trajectory of industrial growth and grid stability.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News