Understanding the Legal Precedent on Leave Encashment
The tax landscape in India frequently witnesses disputes where the interpretation of circulars and notifications shifts the financial burden for retirees. A recent decision by the Chennai Bench of the Income Tax Appellate Tribunal (ITAT) has provided significant relief to non-government employees by allowing the benefit of the enhanced tax exemption limit for leave encashment, even for those who retired prior to the effective date of the government notification.
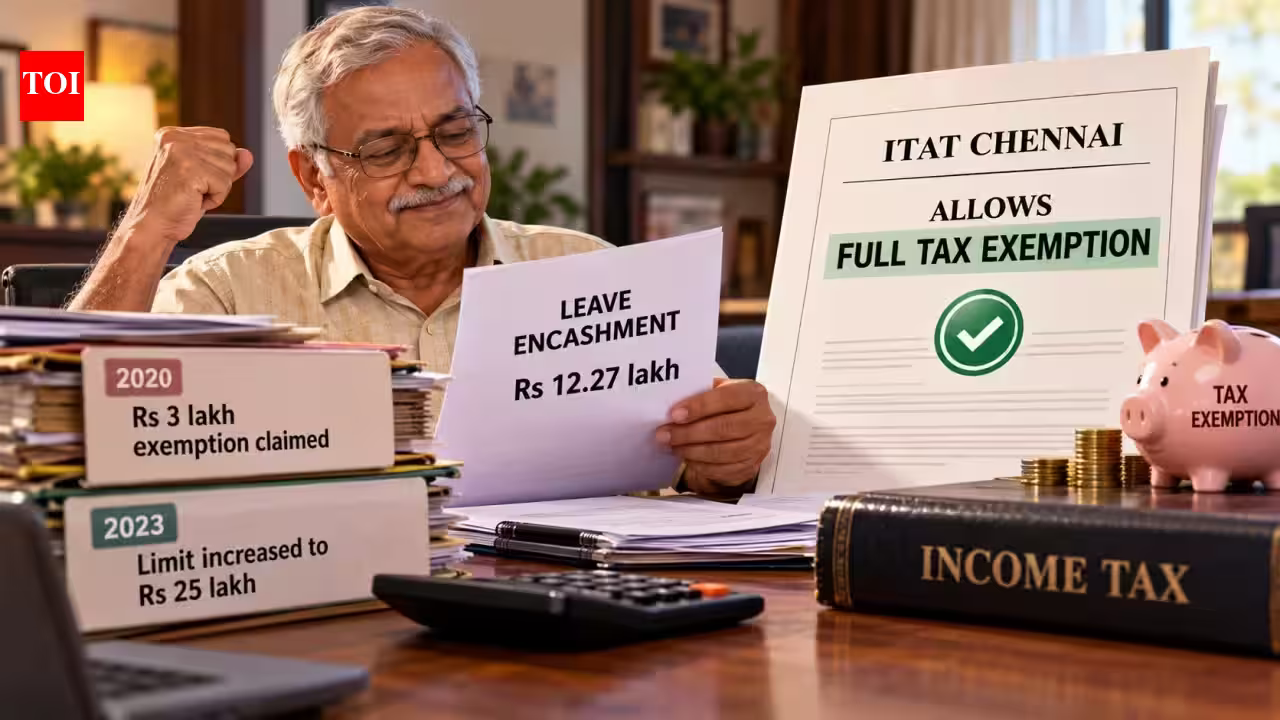
The core of the dispute originated from the Central Board of Direct Taxes (CBDT) Notification No. 31/2023, issued on May 24, 2023. This notification raised the tax exemption threshold for leave encashment for non-government employees from the long-standing limit of Rs 3 lakh to Rs 25 lakh. The government mandated that this change would come into force from April 1, 2023. This created a grey area for employees who had retired before this date but whose tax assessments were either pending or under litigation. The Chennai ITAT ruling serves as a vital touchstone for how tax authorities and tribunals view the “remedial” nature of such amendments when they are intended to mitigate financial hardship.
The Anatomy of the Chennai ITAT Dispute
The case involved a bank employee who retired in the financial year 2019-20. Upon his superannuation, he received a leave encashment payout of Rs 12,27,232. In his income tax return filed for the assessment year 2020-21, he dutifully claimed the prevailing statutory exemption of Rs 3 lakh, paying tax on the balance amount. The Centralised Processing Centre (CPC) in Bengaluru processed the return accordingly.
However, once the government announced the hike to Rs 25 lakh in 2023, the taxpayer sought to revise his position, arguing that he should be entitled to the higher exemption limit. His initial appeal before the Commissioner of Income Tax (Appeals) was rejected on the grounds that the law as it stood during the 2020-21 assessment year dictated the Rs 3 lakh limit. The Chennai ITAT, upon hearing the appeal, took a broader view, focusing on the legislative intent behind the notification. The tribunal held that because the notification was designed to address the inadequacy of a limit that had remained stagnant for two decades, it should be treated as a curative provision that benefits taxpayers retroactively.
The Principle of Remedial Legislation
Legal experts have noted that the ITAT’s decision was heavily influenced by the nature of the amendment. The Rs 3 lakh limit had remained unchanged for nearly 20 years, effectively losing its utility due to inflation and rising salary structures in the private sector. By increasing the limit to Rs 25 lakh, the government acknowledged that the previous threshold was no longer reflective of economic realities.
The ITAT observed that the notification did not introduce a new category of taxpayers or a new form of income; it merely adjusted the monetary ceiling for an existing exemption. Furthermore, the Explanatory Memorandum accompanying the notification contained a critical phrase: that no person should be adversely affected by the change. The Tribunal interpreted this as an intent to provide relief. Under established judicial principles, tax laws that confer a benefit or remove an unintended hardship should be interpreted liberally to ensure justice. Consequently, the absence of an express clause declaring the notification “retrospective” was deemed secondary to its purpose of correcting a long-standing inadequacy.
Market Insights and the Indian Tax Context
In the broader context of Indian business and labor, this ruling highlights a recurring tension between strict statutory interpretation and the equity-based approach favored by tribunals. For the corporate sector, this serves as a reminder that tax planning for retirement benefits is not merely a static exercise. When central authorities issue notifications to “rationalise” existing provisions, it often opens doors for taxpayers to seek redressal for past assessments if the litigation window remains open.
However, the path to claiming such benefits is not entirely clear-cut. Taxpayers must navigate the reality of judicial divergence. While the Chennai ITAT has ruled in favour of the taxpayer, other judicial bodies have sometimes taken a more conservative approach. For instance, in other legal matters, courts have emphasized the importance of the “operative date” mentioned in notifications. Because the Patna High Court, in a separate context, treated the April 1, 2023 date as a strict operative boundary, the legal environment remains nuanced. Consequently, while the Chennai decision is a powerful precedent, it does not function as a blanket guarantee for all retirees across the country without challenge.
Strategic Takeaways for Retirees
For individuals who retired before April 2023 and find themselves in a similar tax position, the Chennai ITAT ruling provides a strong, defensible framework to approach tax authorities. The key takeaway is the importance of keeping tax records and appeals active within the statutory time limits. The taxpayer in the Chennai case was able to secure relief largely because his case was still within the relevant appellate stages.
Tax professionals advise that retirees who find their leave encashment taxed under the old, lower limit should evaluate their specific case status. If an assessment is still under appeal or if there is a window for filing a rectification request, the ITAT’s reasoning—that the amendment is curative and intended to mitigate hardship—can be a compelling argument. Nevertheless, given that some courts still maintain that the operative date of a notification is absolute, taxpayers should prepare for potential litigation. The ruling ultimately underscores that while tax statutes provide the framework, the interpretation of justice by the judiciary remains the final arbiter for addressing imbalances created by outdated financial limits. As Indian tax law continues to evolve, the distinction between “prospective” and “curative” amendments will remain a focal point for those seeking to maximize their post-retirement income.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News