The Critical Distinction Between Under-reporting and Misreporting
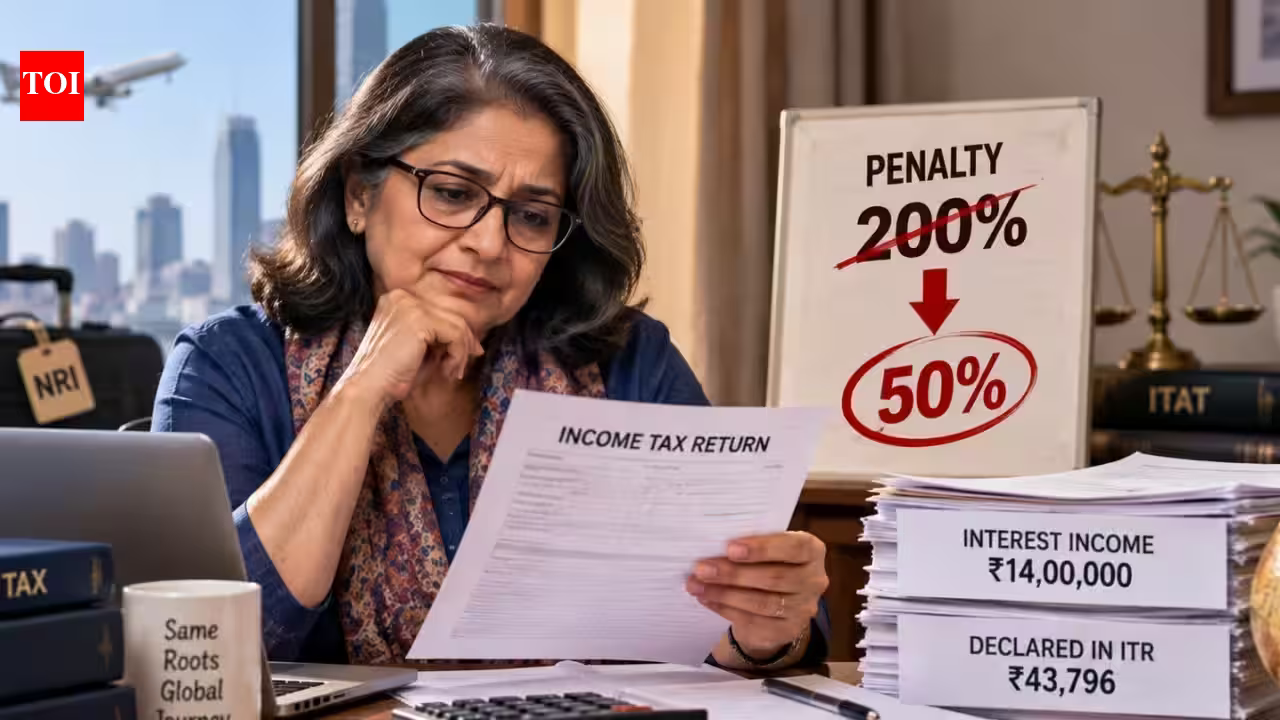
The Indian tax framework, governed by the Income Tax Act, 1961, places a significant emphasis on the accuracy of self-assessment. Section 270A of the Act represents a cornerstone of current tax administration, delineating the penalties applicable when a taxpayer fails to report income correctly. The recent case of a non-resident Indian (NRI) woman, whose penalty was reduced by the Income Tax Appellate Tribunal (ITAT) Mumbai from 200% to 50%, serves as a vital lesson for taxpayers regarding the nuance of tax compliance.
Under Section 270A, the law distinguishes between two distinct categories of default: under-reporting and misreporting. This distinction is not merely academic; it has massive financial implications. Under-reporting typically attracts a penalty equivalent to 50% of the tax payable on the under-reported income. Conversely, misreporting—which implies a deliberate act or a lack of bona fide intent—triggers a penalty of 200%. The legal battle in this case underscores that the Revenue Department cannot automatically classify an omission as “misreporting” simply because the income was detected during a reassessment process.
For businesses and individuals alike, the takeaway is clear: the burden of proof rests on the tax authorities to demonstrate that the omission falls within specific criteria defined under the law. An omission, even one involving a substantial amount, does not automatically equate to a fraudulent intent to evade taxes.
The Role of Third-Party Intermediaries and Accountability
A recurrent challenge for taxpayers, particularly those living abroad or busy professionals, is the reliance on third-party intermediaries such as chartered accountants or tax consultants. In the case at hand, the taxpayer argued that her omission of Rs 14.02 lakh in interest income was the result of a failure by her tax professional rather than a deliberate attempt to conceal wealth.
While the ITAT Mumbai recognized that this reliance led to an unfortunate outcome, it is essential to note that the law generally holds the taxpayer as the primary party responsible for the accuracy of their Income Tax Return (ITR). Outsourcing the compliance process does not absolve the assessee of the duty to review their filings. In the Indian business context, where the Income Tax Department has moved to fully digital, automated, and faceless assessment processes, reliance on legacy methods of communication—or trusting an accountant blindly without oversight—poses a significant financial risk.
The tribunal’s decision to provide relief was based on the “peculiar circumstances” of the case, specifically the lack of technical awareness and the taxpayer’s eventual cooperation upon becoming aware of the liability. However, taxpayers should not assume that blaming a consultant will always result in a reduced penalty. The onus remains on the assessee to ensure that all interest income, rental income, and other accruals are captured in the tax computation.
Navigating the Digital Tax Environment
The shift toward electronic notices and the Faceless Assessment Scheme has transformed the landscape of Indian tax administration. Many taxpayers, especially those residing outside India, remain accustomed to traditional methods of correspondence and may overlook digital alerts issued on the Income Tax portal. This case highlights how failing to monitor the portal can lead to a snowball effect, where an initial innocent omission is perceived by the department as a willful disregard for tax obligations.
For NRIs, the complexity is compounded by global income considerations and the intricacies of Double Taxation Avoidance Agreements (DTAA). The fact that the taxpayer in this instance had ignored electronic notices initially emboldened the Assessing Officer to view the omission as a deliberate misreporting. The ITAT’s intervention highlights an important protection: the law is not intended to be a mechanism for crushing taxpayers over procedural lapses, provided that the underlying intent is not malicious. However, proactive management of one’s tax account on the Income Tax e-filing portal is no longer an optional task—it is a mandatory requirement for maintaining compliance.
The Nuances of Penalty Adjudication
The reduction of the penalty from 200% to 50% is a significant relief, but it is equally important to highlight what the taxpayer did right in this situation. Once the discrepancy was identified, she took immediate action to settle the tax liability and the associated interest. This demonstration of good faith played a critical role in the tribunal’s decision-making process.
In the Indian legal system, penalties under Section 270A are designed to serve as a deterrent against tax evasion. When a taxpayer settles their dues upon realizing a mistake, it complicates the Revenue’s argument that there was a wilful attempt at concealment. The ITAT’s decision clarifies that the higher 200% rate is reserved for cases involving the suppression of information, the failure to record investments, or the submission of inaccurate evidence. A simple omission of interest income, even when large, does not automatically cross that threshold if the taxpayer presents a consistent and plausible explanation.
Best Practices for Future Compliance
To avoid the stress and financial drain of penalty litigation, taxpayers should implement a rigorous, standardized approach to their annual filings. Firstly, cross-verifying the Annual Information Statement (AIS) and the Taxpayer Information Summary (TIS) is mandatory. These documents aggregate data from banks, financial institutions, and other entities, providing a clear roadmap of the income that the tax department is already aware of. If the details in the ITR do not match the AIS, it is a red flag that will almost certainly trigger an automated notice.
Secondly, maintaining clear communication channels with tax consultants is vital. If a professional is managing the file, the taxpayer should request a summary of the income being declared to ensure that interest from NRO/NRE accounts or other sources has not been missed.
Finally, the resolution of this case illustrates that while the law is stringent, it is not inherently unjust. The tax machinery in India is becoming increasingly data-driven, and while this leads to better detection of under-reporting, it also provides a clearer framework for adjudication. Taxpayers who remain vigilant, respond promptly to notices, and address discrepancies with transparency are significantly better positioned to defend their interests before the appellate authorities. By prioritizing documentation and digital awareness, taxpayers can navigate the complexities of the Income Tax Act without falling victim to exorbitant penalties.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News