The Significance of Institutional Oversight in Corporate Governance
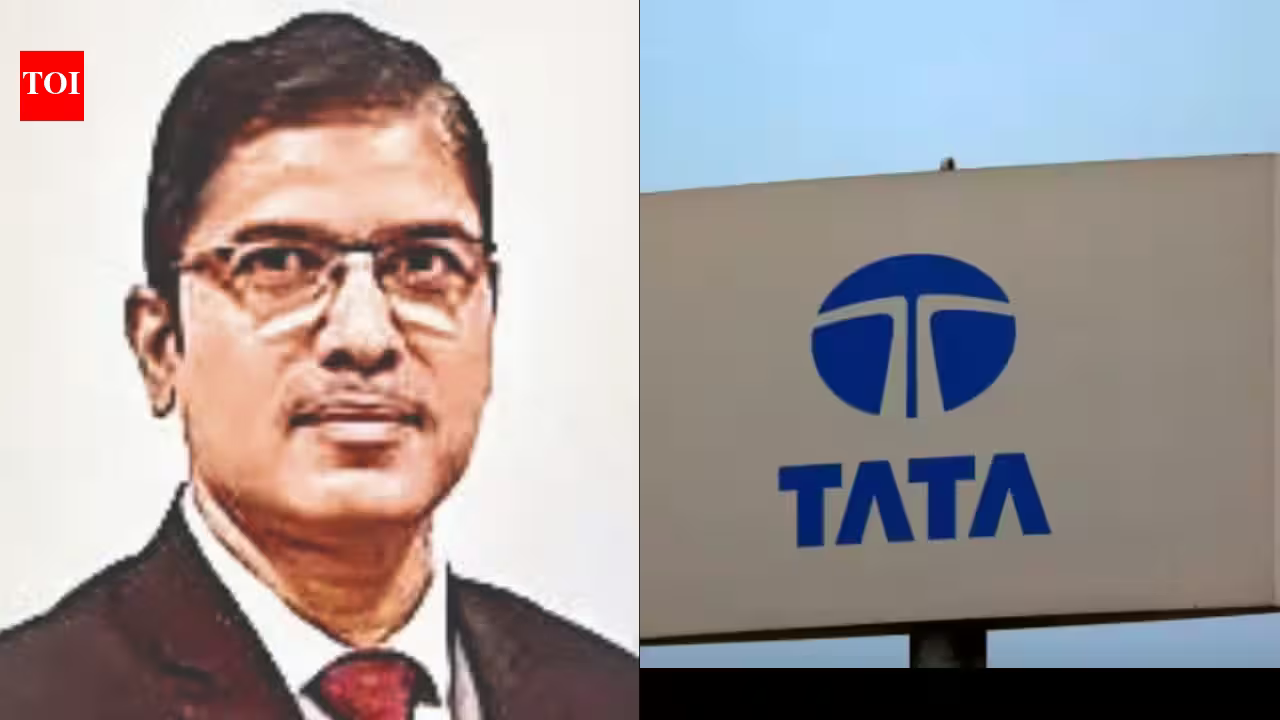
In the complex ecosystem of Indian conglomerate structures, the role of public trusts is often overlooked until they become the epicenter of a high-stakes legal confrontation. The recent interventions by Maharashtra Charity Commissioner Amogh Shyamkant Kaloti into the internal affairs of the Tata Trusts have brought the mechanics of the Maharashtra Public Trusts Act, 1950, into the national spotlight. For investors, corporate legal teams, and regulatory observers, this development serves as a stark reminder that even the most established organizations are subject to the oversight of quasi-judicial authorities when public interest and charitable governance are at stake.
The Tata Group, an iconic institution holding a dominant 66.4% stake in the conglomerate through its philanthropic arms, operates within a unique governance framework. When the legality of trustee appointments, board meeting protocols, and historical share transfers is challenged, the Charity Commissioner is the primary authority tasked with adjudication. This process underscores the intersection between private corporate control and public regulatory compliance. It reinforces the reality that in India, the distinction between philanthropic intent and corporate management is not merely a matter of company policy but a matter of statutory regulation.
Understanding the Role of the Charity Commissioner
The Office of the Charity Commissioner is a quasi-judicial body created under the Maharashtra Public Trusts Act. While its functions often remain focused on routine administrative tasks such as registering trusts, auditing annual financial statements, and monitoring hospital charity beds, its statutory mandate extends to the investigation of financial misconduct and the potential suspension of trustees. This authority is equivalent to that of a district judge, providing the office with the power to compel compliance and issue orders that can disrupt the operations of even the most powerful philanthropic foundations.
For the Tata Trusts, which manage a significant portion of the wealth supporting the Tata Group’s global operations, the oversight of the Charity Commissioner represents a critical procedural hurdle. When complaints regarding governance are filed, the office is required to weigh the fiduciary responsibilities of the trustees against the established bylaws of the trust deeds. The methodical, book-by-book approach adopted by officials like Amogh Kaloti reflects a judiciary-led oversight model that prioritizes legal adherence over the convenience of corporate decision-making. This process is inherently slow and deliberate, often lasting months, which poses a significant risk to the agility of corporate strategy when trust leadership is in dispute.
The Intersection of Legacy Trusts and Modern Governance
The complaints filed by stakeholders such as Venu Srinivasan and Mehli Mistry highlight a growing tension between traditional trust governance and the expectations of modern corporate accountability. Many of these trusts were established decades ago under legal frameworks that may not have anticipated the scale or the competitive demands of a global conglomerate in the 21st century. As the composition of these boards changes and new generations of leadership take the helm, historical documentation—such as share transfers from 1989—often faces intense forensic scrutiny.
The recent ruling validating the transfer of shares from the Navajbai Ratan Tata Trust to Naval Tata suggests that the current oversight process is intent on verifying historical legitimacy. However, the pending issues regarding the number of permanent trustees on the board of the Sir Ratan Tata Trust (SRTT) indicate that structural governance matters remain volatile. These disputes are not merely personal disagreements between influential figures; they are foundational challenges to the control structure of the Tata Group. Any change in the composition of these boards has direct implications for the parent company, highlighting how administrative decisions within a public trust can cascade into the boardroom of a massive multinational corporation.
Legal Precedents and the Risks of Administrative Scrutiny
The intervention in the Tata Trusts demonstrates a shift toward more proactive regulatory oversight in India. Historically, trusts have enjoyed a degree of autonomy that allowed for relatively seamless succession and management. The current environment, marked by an increased focus on transparency and institutional compliance, suggests that this autonomy is shrinking. The legal process initiated by the Charity Commissioner indicates that courts are willing to halt board activities, such as prohibiting the convening of board meetings, if there is a prima facie case of governance non-compliance.
For businesses operating through trust structures, this creates a tangible risk of operational paralysis. When a regulatory body pauses the decision-making apparatus of an entity that holds a majority stake in a public company, the potential for market instability increases. Observers must recognize that the Charity Commissioner’s office operates independently of market sentiments. Its function is to interpret the letter of the law as it pertains to public and charitable interests, regardless of the impact on the stock market or corporate branding. This disconnect between regulatory timing and market requirements is a defining feature of the current Indian legal landscape.
Strategic Implications for Indian Corporate Entities
The ongoing situation serves as a cautionary tale for large Indian conglomerates and family-owned businesses that utilize trust models for asset management and control. The primary takeaway is the necessity of impeccable documentation and governance hygiene. When legal challenges arise, they are often directed at the historical legitimacy of governance protocols. If trust deeds, share transfer records, and board appointment procedures are not maintained with absolute precision, they become vulnerable to prolonged litigation before authorities like the Charity Commissioner.
Furthermore, the involvement of officials like Amogh Kaloti—who possess a background in both law and public administration—signals a trend where such roles are being occupied by individuals with rigorous legal training. This professionalization of regulatory oversight suggests that “business as usual” approaches to governance will face increasingly tough scrutiny. Organizations must now integrate regulatory compliance into their core strategy, treating the oversight of a Charity Commissioner with the same urgency as audit and taxation requirements.
Ultimately, the resolution of these disputes will establish important precedents for how philanthropy and corporate control coexist in India. By bringing the administration of the Tata Trusts under judicial review, the authorities are asserting that there is no space for ambiguity in the management of institutions that control vast public assets. For the wider Indian business community, this episode reinforces the imperative to modernize governance frameworks, anticipate regulatory inquiries, and ensure that every board action can withstand the scrutiny of an independent, law-driven, and patient administrative authority.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News