Understanding the Mechanics of Recent Rupee Volatility
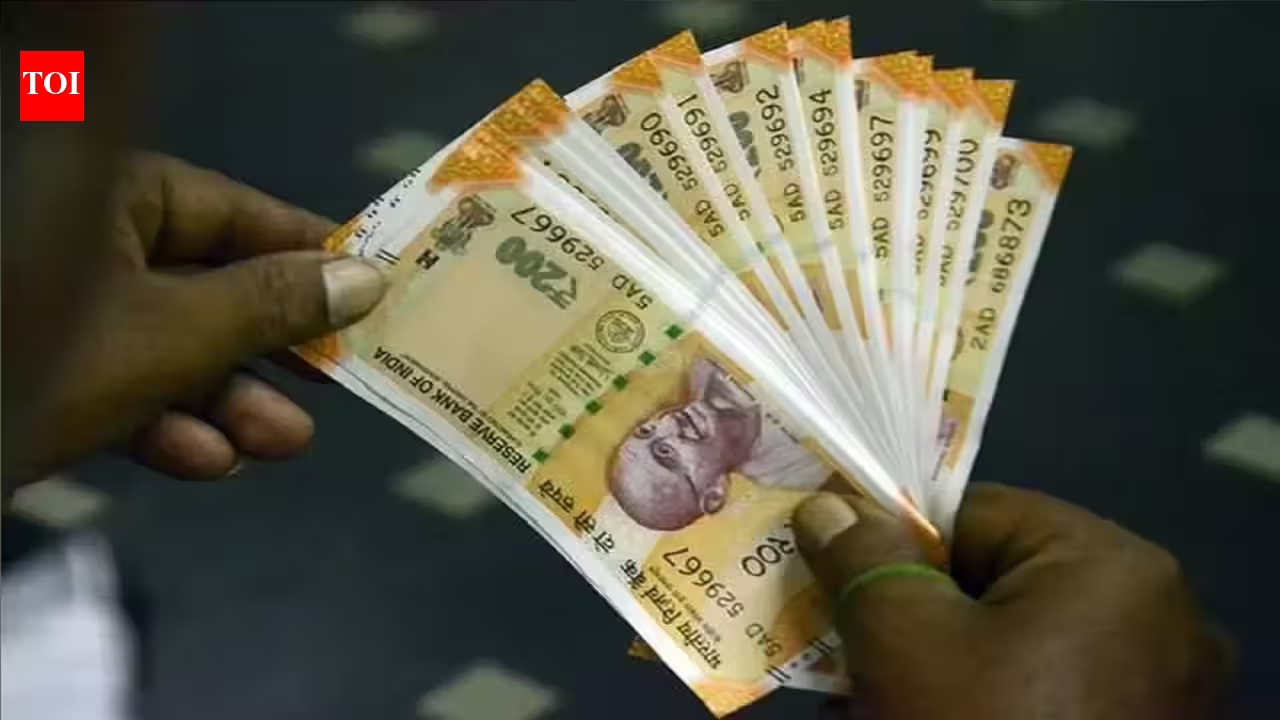
The Indian rupee has experienced a significant surge, gaining 96 paise against the dollar to reach 95.77 in recent trading sessions. This sharp appreciation marks one of the most substantial single-day gains for the currency in the last six months and ranks among the top five movements observed over the past five years. While this reversal provides a brief reprieve for policymakers, the underlying economic architecture remains under considerable strain. The rupee’s performance this year, characterized by an approximate 6.5 percent depreciation, highlights the structural challenges posed by global macroeconomic headwinds and internal liquidity pressures.
The sudden rally is largely attributed to proactive, if controversial, interventions by the Reserve Bank of India (RBI). By implementing restrictive measures aimed at curbing speculative dollar demand and tightening the availability of foreign exchange, the central bank has effectively forced market participants to unwind short positions. However, such interventions often produce a bifurcated impact: while they provide immediate support to the currency, they simultaneously introduce friction into the banking system, increasing compliance burdens and complicating the day-to-day operations of financial institutions.
The Regulatory Tug-of-War Between RBI and Commercial Banks
The efficacy of recent foreign exchange regulations has become a point of contention between the central bank and the banking sector. The Foreign Exchange Dealers’ Association of India (FEDAI) has formally petitioned the RBI, requesting both a relaxation of the current mandates and an extension of the compliance timeline. Banks are grappling with a dual challenge: the operational complexity of integrating new, granular documentation requirements and the economic impact of increased reserve maintenance.
From a business perspective, the primary concern for banks lies in the transition costs. Financial institutions are being asked to develop customized products and reporting mechanisms to align with the new regulatory framework. Furthermore, the requirement to maintain 99 percent of daily cash reserves with the RBI—a tightening from the previous 90 percent threshold—directly impacts liquidity management. Banks argue that the cost of capital tied up in these reserves, coupled with the uncertainty regarding pricing these new compliance costs for end-customers, creates an unpredictable environment. The industry’s push for clarity is not merely a request for leniency but a pragmatic necessity to ensure that the transmission of monetary policy does not stifle the operational efficiency of the banking system.
Macroeconomic Drivers and the Persistent Trade Deficit
While central bank intervention can steer currency markets in the short term, the long-term trajectory of the rupee is dictated by fundamental macroeconomic factors. The widening trade deficit remains the most critical anchor pulling the currency downward. India’s structural reliance on energy imports, particularly crude oil, makes the rupee highly sensitive to global commodity price fluctuations. As oil prices remain elevated, the demand for dollars among Indian oil marketing companies creates persistent downward pressure on the local currency.
Beyond the trade balance, foreign portfolio outflows represent a significant variable in the rupee’s stability. When global interest rate environments shift or when domestic growth projections are perceived as softening, capital often migrates toward perceived safe-haven assets, such as the US dollar. This exodus forces the RBI to manage the balance of payments with finite foreign exchange reserves. Therefore, the sustainability of the recent recovery depends less on temporary regulatory curbs and more on the stabilization of global energy markets and the consistent inward flow of foreign direct investment. Without a meaningful contraction in the trade deficit or a sustained recovery in capital account inflows, the current currency appreciation may be viewed as a technical correction rather than a shift in long-term momentum.
Monetary Policy Tightening and the Bond Market Response
The ripple effects of the RBI’s recent actions have extended beyond the foreign exchange markets, significantly impacting the debt market. As the central bank tightens liquidity through its new reserve maintenance mandates, the cost of funds is expected to rise. This has manifested in an upward movement in bond yields, with the 10-year benchmark yield climbing toward 7.39 percent. For corporations and the government, higher yields signify increased borrowing costs, which could potentially dampen capital expenditure and economic growth.
The market response suggests a growing apprehension regarding further monetary tightening. Investors are weighing the benefit of a stabilized rupee against the potential cost of a constrained monetary environment. If yields continue to rise, the banking sector may face an additional layer of pressure: balancing the need to support the rupee with the imperative to maintain healthy credit growth. The central bank is essentially walking a tightrope, attempting to defend the currency without triggering an interest rate shock that could derail private investment cycles.
Strategic Outlook: Sustainability vs. Intervention
Looking ahead, the Indian business landscape must prepare for a period of continued volatility and regulatory scrutiny. For corporates engaged in international trade, the current environment necessitates robust hedging strategies and a heightened focus on liquidity management. Relying on the stability of the rupee without a commensurate shift in fundamental economic indicators is a risky proposition. The focus for businesses should be on operational agility—ensuring that supply chain costs and import-related expenditures are shielded from currency fluctuations through disciplined financial planning.
The RBI’s current stance serves as a signal that it is willing to tolerate short-term market friction to maintain exchange rate order. However, the ultimate success of these measures will be measured by the ability of the economy to absorb these shifts without sacrificing liquidity or credit flow. As banks and regulators negotiate the final implementation details, the market will likely remain in a state of cautious adjustment. Investors and business leaders should prioritize monitoring two specific indicators: the monthly trade data, which will provide clues on the demand for foreign currency, and the RBI’s subsequent liquidity management operations, which will reveal the extent to which they are willing to prioritize currency defense over interest rate stability. In this complex ecosystem, the rupee’s path will remain tethered to the fragile balance between national policy objectives and the global forces of the open market.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News