Understanding Leave Encashment and Tax Liability in India
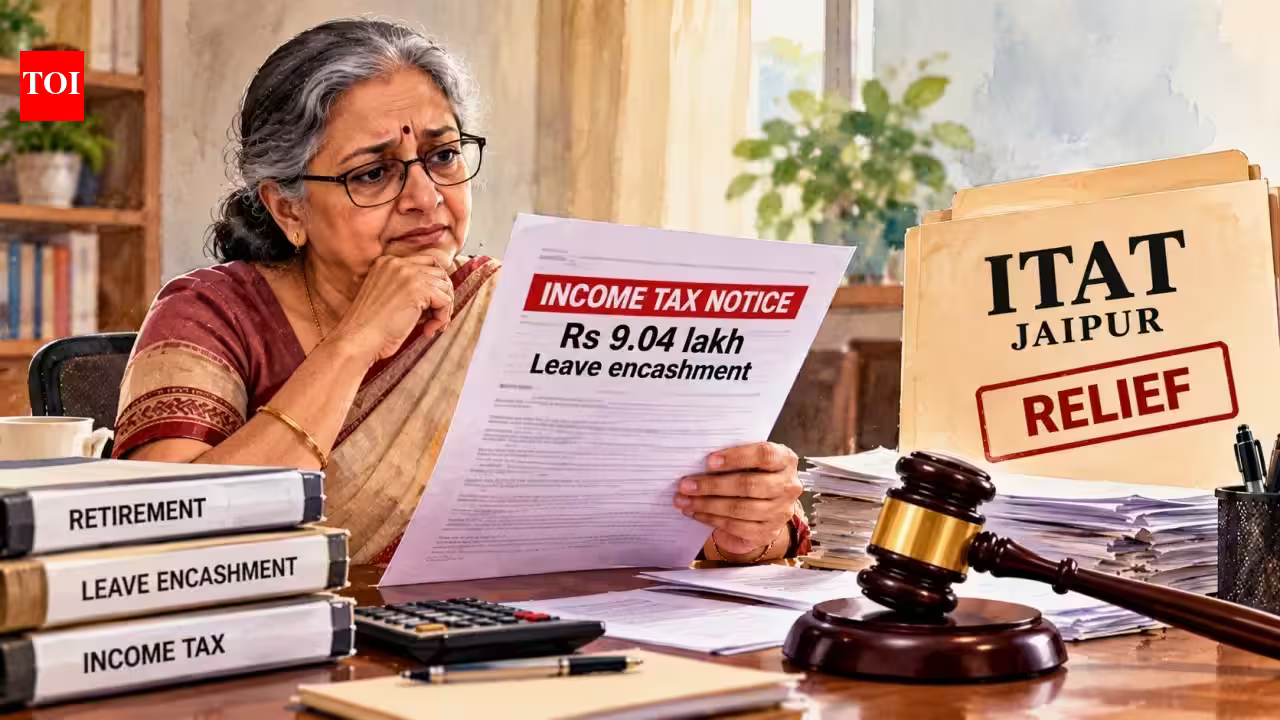
The taxation of terminal benefits, particularly leave encashment, remains a critical area of financial planning for retiring professionals in India. The recent ruling by the Income Tax Appellate Tribunal (ITAT) in Jaipur highlights not only the complexities of tax law but also the importance of procedural compliance. In this case, a retired employee of the Life Insurance Corporation of India (LIC) faced a tax demand because the Income Tax Department classified her as a non-government employee, restricting her exemption limit to Rs 3 lakh.
In India, the tax treatment of leave encashment is governed by Section 10(10AA) of the Income Tax Act. For central and state government employees, the entire amount received as leave encashment upon retirement is fully exempt from income tax. However, for non-government employees, including those in the private sector and public sector undertakings, the exemption is subject to specific statutory limits. Understanding these classifications is essential for retirees to ensure accurate tax filing and avoid unwanted scrutiny from tax authorities.
The Evolution of the Exemption Ceiling
Historically, the exemption limit for leave encashment for non-government employees was set at Rs 3 lakh. This threshold remained in place for many years, failing to keep pace with inflation and the rising salary structures of the modern workforce. Recognizing this discrepancy, the Union Budget 2023 introduced a significant change, elevating the tax-free limit for leave encashment to Rs 25 lakh.
The legislative change was intended to provide relief to retirees who accumulate substantial leave balances over long careers. For the taxpayer in the Jaipur case, the confusion stemmed from the timing of her retirement—June 2020—and her subsequent tax filing. While the lower limit of Rs 3 lakh was the prevailing law at the time of her retirement, the subsequent judicial interpretation and the government’s shift toward a more taxpayer-friendly ceiling created a window for relief. The ITAT’s decision to allow the exemption up to the higher ceiling underscores the evolving nature of tax administration, where courts often lean toward the intent of the legislation, which is to provide financial security to retiring individuals.
The Role of Professional Representation and Procedural Delays
One of the most significant aspects of the recent ITAT ruling is the condonation of a 1,277-day delay in filing the appeal. In the Indian legal and tax system, administrative delays are often met with strict scrutiny. The Income Tax Department frequently opposes applications for condonation of delay, arguing that taxpayers must be vigilant regarding their financial obligations.
However, the ITAT Jaipur adopted a more nuanced perspective, emphasizing that an individual should not be penalized for the negligence of a tax consultant. Many taxpayers in India rely heavily on chartered accountants or tax practitioners to handle correspondence with the Income Tax Department. When a professional fails to communicate crucial updates—such as the dismissal of an appeal—the taxpayer is left vulnerable to significant financial demands. By citing the Supreme Court’s precedent in the case of Collector, Land Acquisition v. Mst Katiji, the tribunal reaffirmed that the law should be applied with a degree of pragmatism. This ruling serves as a vital reminder to professionals that procedural lapses by intermediaries should not serve as an absolute barrier to justice for the taxpayer.
Implications for Taxpayers and Compliance Strategy
This case highlights the risks associated with passive tax management. For retirees and employees nearing the end of their service, it is insufficient to simply rely on external consultants. Taxpayers must ensure they are aware of the status of their assessments and the notices received from the tax department. The transition from the old exemption regime to the current Rs 25 lakh limit requires careful verification of when the income was received and which financial year is being assessed.
Furthermore, the taxation of excess leave encashment—amounts exceeding the exempt threshold—must be managed correctly. Any sum above the limit is taxed as “salaries” at the individual’s applicable slab rate. In a country where tax rates can reach 30 percent plus applicable surcharges and cess, the tax impact of a large, one-time payout can be substantial. Proper tax planning, which includes understanding the specific sections of the Income Tax Act that apply to one’s employer type, is the only way to mitigate these liabilities effectively.
Navigating Future Disputes with the Taxman
The Jaipur tribunal’s decision is a positive development for taxpayers who may have fallen behind on procedural requirements due to poor professional guidance. It reinforces the principle that the tax department should function as a facilitator of tax collection rather than an obstacle to legitimate claims. Nevertheless, the lesson for the business and professional community is clear: documentation and oversight are paramount.
When dealing with large terminal benefits, it is advisable to keep detailed records of all communications, including appointment letters, retirement terms, and any correspondence with the tax authorities. If a dispute arises, seeking independent legal or financial counsel to review the merits of the case—rather than relying solely on the previous consultant—can lead to a much more favorable outcome. As tax laws continue to be updated in response to economic conditions, taxpayers must remain informed about current exemptions. Relying on outdated knowledge or assuming that all employees are treated equally under the tax code can lead to unnecessary disputes, financial penalties, and long-drawn-out legal proceedings that could have been avoided with proactive management.
In conclusion, while the judiciary has shown a willingness to accommodate the challenges faced by individual taxpayers, the burden of ensuring compliance and monitoring professional service providers remains squarely on the shoulders of the assessee. By staying informed and maintaining a vigilant approach to tax filing, Indian professionals can secure their retirement benefits and navigate the complexities of the Income Tax Act with confidence.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News