The Evolution of Tax Rebates and Special Rate Income
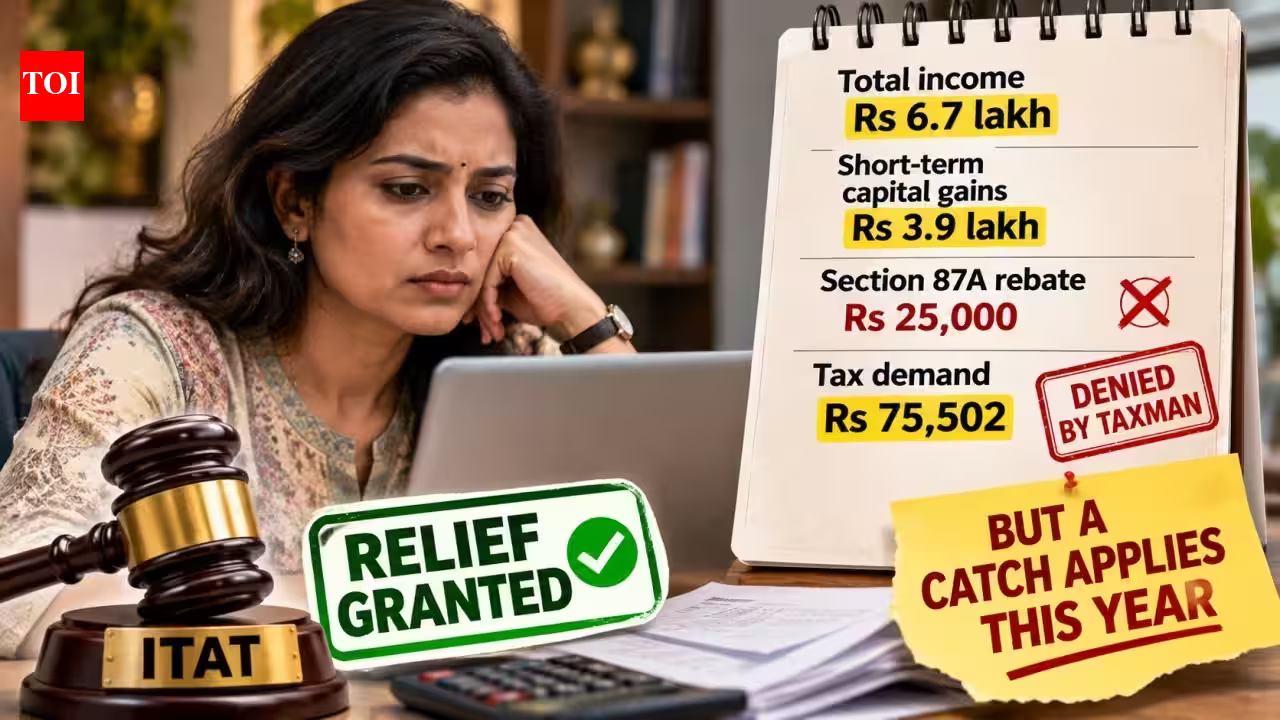
The intersection of individual investment behavior and complex tax legislation often leads to litigation, as evidenced by a recent landmark ruling by the Income Tax Appellate Tribunal (ITAT), Hyderabad. At the core of this dispute was the eligibility for a rebate under Section 87A of the Income-tax Act, 1961, when a taxpayer’s total income includes short-term capital gains (STCG) taxable at a special rate under Section 111A.
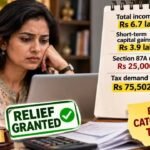
For many middle-income earners in India, the shift toward market-linked investments has become a standard practice. However, when these investments yield returns that are subject to specific tax treatment, the calculation of the final tax liability often becomes a point of contention with the Centralised Processing Centre (CPC). The recent case involving a taxpayer who earned Rs 6.7 lakh—of which Rs 3.9 lakh comprised STCG—highlights the friction between the taxpayer’s interpretation of statutory provisions and the revenue department’s rigid administrative directives.
The taxpayer’s argument rested on a foundational principle of fiscal law: that unless a statute explicitly bars a benefit, a tax authority cannot deny it through interpretation or administrative circulars. By opting for the new tax regime under Section 115BAC(1A), the taxpayer sought a Rs 25,000 rebate. The rejection of this claim by the authorities, and its subsequent reversal by the ITAT, underscores the critical role of judicial oversight in safeguarding taxpayer rights against overreaching administrative constraints.
Analyzing the ITAT’s Jurisprudential Stance
The ITAT’s decision to rule in favor of the taxpayer was driven by a strict constructionist approach to the Income-tax Act. The tribunal examined Section 87A and Section 115BAC(1A) and found an absence of express language prohibiting the rebate simply because the total income included gains taxable at the special rate of 15% under Section 111A.
In its reasoning, the tribunal noted that the tax authorities failed to identify any statutory provision that restricted the Section 87A rebate when applied to a tax liability that encompasses special-rate income. The ruling drew strength from established judicial precedents, including previous decisions from the Ahmedabad and Mumbai benches of the ITAT, which had consistently maintained that administrative circulars cannot override the plain text of the law.
This ruling serves as a reminder that the Income-tax Act operates on the authority of legislation passed by Parliament. When the Department of Revenue issues a circular—such as Circular No. 13/2025—that seeks to restrict a benefit not mentioned in the primary legislation, the judiciary will often prioritize the statutory text over the circular. The ITAT’s decision reaffirmed that a taxpayer meeting the income threshold criteria is entitled to the rebate regardless of the composition of their income, provided the Act does not explicitly state otherwise for that specific assessment year.
The Limitations of Circulars in Tax Administration
A recurring theme in Indian tax litigation is the tension between the Central Board of Direct Taxes (CBDT) circulars and the actual provisions of the Income-tax Act. While circulars are intended to clarify the application of the law and provide guidance to tax officers, they are frequently used as instruments to streamline assessment processes, sometimes at the cost of taxpayer benefits.
The Hyderabad ITAT decision reinforces the principle that the law is superior to administrative instruction. For the taxpayer in this case, the ruling was a victory of technical precision. By successfully arguing that the rebate was a statutory entitlement, the taxpayer highlighted that the government cannot effectively amend the law via internal circulars or adjustments in the electronic filing utility used by the CPC.
However, from a business and policy perspective, this creates a state of uncertainty. Taxpayers and their consultants often rely on the automated systems and circulars of the revenue department for compliance. When these systems disagree with the law, it necessitates costly litigation. For the average investor, the cost of challenging a denial of Rs 25,000 can be prohibitive, making the ITAT’s role in providing accessible legal interpretation vital for the health of the Indian tax ecosystem.
The Regulatory Pivot: Why the Landscape is Changing
While the ITAT ruling provides clarity for past assessment years, it simultaneously serves as a harbinger of change. The legislative response to such legal interpretations is often swift. Recognising that taxpayers were successfully arguing for rebates against special-rate income, the government intervened through the Finance Act, 2025.
The Finance Act has now explicitly restricted the Section 87A rebate, mandating that it be applied only to tax calculated at specified slab rates. This legislative amendment effectively closes the window that the ITAT ruling had previously opened. As of the current fiscal cycle, the rebate is no longer applicable against tax payable on special-rate income, such as STCG under Section 111A.
This development highlights the dynamic nature of Indian tax policy. The government’s intent is clearly to streamline the new tax regime and prevent the “dilution” of tax revenue that occurs when rebates are applied to income categories that are already taxed at concessional rates. For the taxpayer, this means that while the ITAT decision remains a significant win for historical disputes, it serves as a warning for future financial planning.
Strategic Implications for Indian Taxpayers
As India continues to transition toward a simplified but more rigid tax structure, taxpayers must adapt their financial strategies. The era of claiming broad rebates against complex income streams is rapidly coming to an end. Investors should now factor in the full impact of special-rate taxes on capital gains without the expectation of offsetting these liabilities through Section 87A rebates.
For those navigating the new tax regime, the takeaway is twofold. First, the importance of keeping abreast of legislative amendments cannot be overstated. Relying on past case laws or outdated interpretations can lead to unpleasant surprises during the assessment process. Second, the reliance on the “blanket” nature of tax rebates is no longer a viable strategy for tax optimization.
Financial advisors and taxpayers must now perform more granular calculations when declaring income. Since the Finance Act, 2025 has cemented the separation between slab-rate income and special-rate income for the purpose of rebates, investors should view these categories as distinct tax buckets. By understanding that special-rate income is effectively “ring-fenced” from standard relief measures, individuals can better anticipate their net-of-tax returns. While the legal victory at the ITAT was significant, the current regulatory environment demands a disciplined, forward-looking approach to compliance, moving away from the assumption that administrative loopholes will remain viable for long.
Disclaimer: This content is auto-generated for informational purposes only.
Source: Read Original News